The 2019 Private SaaS Company Survey Results Unveiled in Partnership with KBCM Technology Group

The enterprise software landscape continues to undergo rapid transformation, driven by shifting go-to-market strategies, capital efficiency demands, and evolving customer acquisition models. For the seventh consecutive year, industry publication forEntrepreneurs has partnered with KBCM Technology Group—formerly known as Pacific Crest Securities—to release comprehensive insights into the financial and operational metrics of private Software-as-a-Service (SaaS) companies. The latest installment draws from an extensive survey of approximately 424 private SaaS enterprises, offering a granular look at the benchmarks that define modern cloud-based businesses.
The collaborative initiative, supported by survey participants and coordinated by figures such as David Spitz of KBCM Technology Group, serves as a vital compass for founders, venture capitalists, and institutional investors. As private SaaS companies scale from early-stage ventures to major market players, navigating the delicate balance between hyper-growth and capital consumption remains a central operational challenge. The 2019 survey report provides an exhaustive breakdown of these dynamics, highlighting organic Annual Recurring Revenue (ARR) growth, sales and marketing (S&M) efficiency, customer acquisition cost (CAC) ratios, and infrastructure delivery trends.
A Comprehensive Portrait of Survey Participants
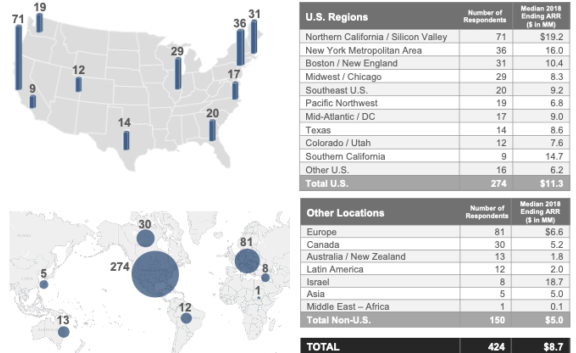
To contextualize the median metrics reported in the 2018 dataset, analysts must first examine the composition of the participating enterprises. The survey captures a diverse cross-section of the global private SaaS ecosystem, though the vast majority of respondent headquarters remain concentrated in North America, reflecting the prevailing geography of venture-backed technology innovation.
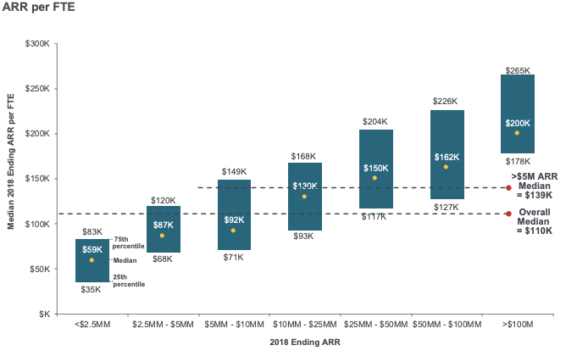
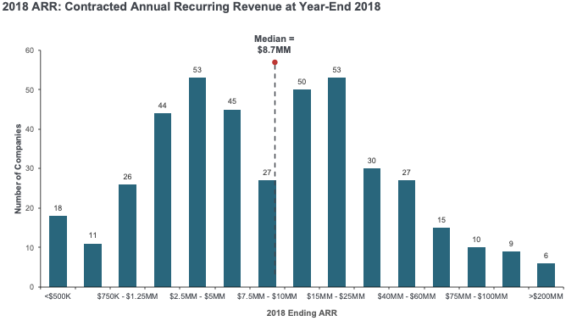
In terms of scale, the respondent pool spans a wide spectrum of ARR brackets. Companies generating less than $2.5 million in ARR form a substantial portion of the dataset, alongside robust representation from mid-market firms ranging from $10 million to $25 million in ARR. At the upper end of the spectrum, a select group of mature enterprises with over $100 million in ARR contributed to the findings, providing valuable benchmarks for late-stage scaling. Human capital efficiency, measured by ARR per full-time equivalent (FTE) employee, further illuminates how effectively these organizations deploy workforce resources as they expand their operational footprints.
Organic ARR Growth and the Growth-Burn Tradeoff
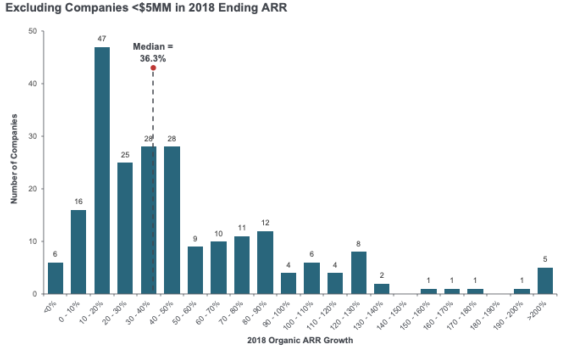
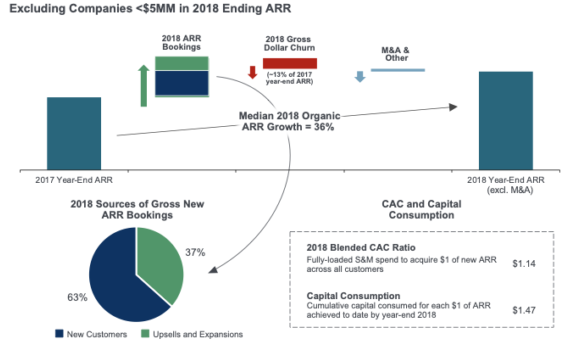
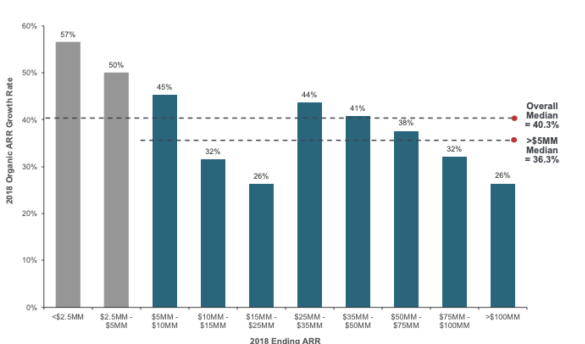
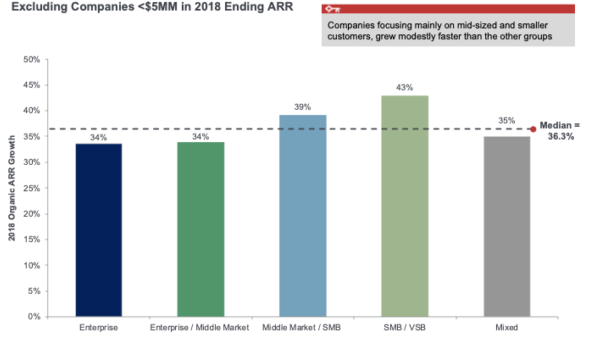
Growth remains the primary valuation driver for SaaS companies, yet the path to achieving it varies significantly based on market focus and contract architecture. According to the 2018 survey data, organic ARR growth—excluding the impacts of mergers and acquisitions—demonstrated wide dispersion across the cohort. While top-quartile performers achieved aggressive expansion rates, the median organic ARR growth rate served as the benchmark for a healthy, scaling cloud business.
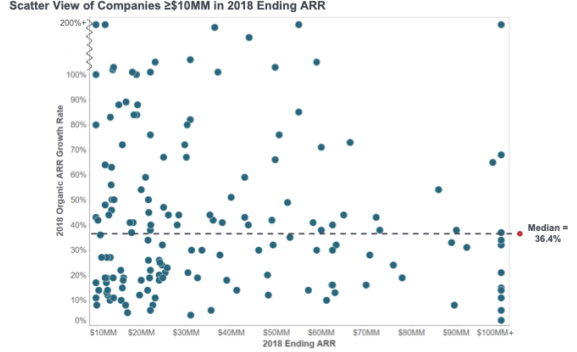
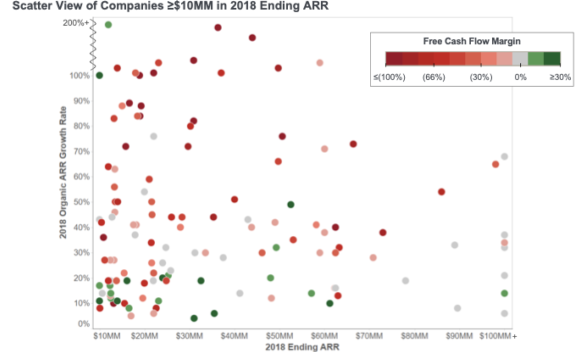
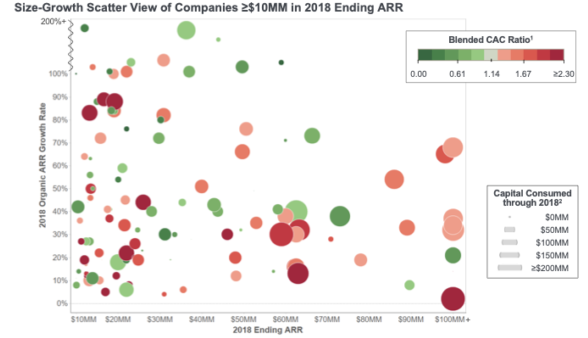
However, rapid expansion rarely comes without a cost. The survey highlights the perennial tradeoff between growth and capital burn. Companies pursuing hyper-growth frequently outpace their revenue generation through heavy investments in sales infrastructure, product development, and customer acquisition. The In-Year Capital Consumption Ratio and Cumulative Capital Consumption Ratio metrics illustrate how much primary equity and debt financing companies burn to achieve their respective growth trajectories.
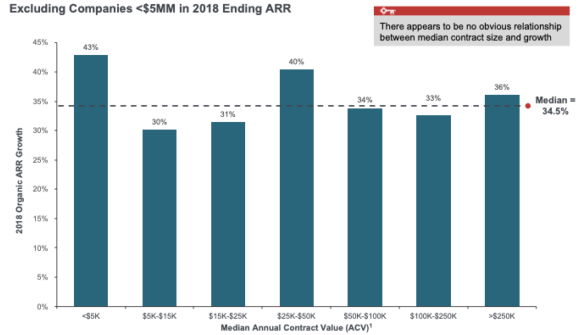
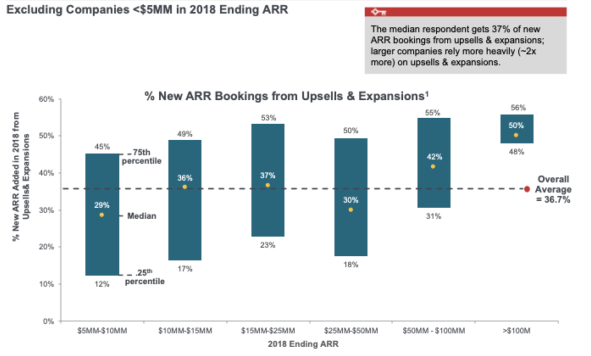
Furthermore, the data underscores a distinct correlation between Annual Contract Value (ACV) and growth velocity. Organizations targeting enterprise-level clients—defined as customers with more than 1,000 employees—frequently navigate longer sales cycles but benefit from higher contract values. Conversely, companies focused on Small and Medium Businesses (SMBs) or Very Small Businesses (VSBs) rely on high-volume, transactional sales motions. The reliance on upsells and expansions also plays a pivotal role; mature SaaS firms increasingly look to their existing customer bases to drive net revenue retention, offsetting churn through strategic cross-selling and modest price increases.
Go-To-Market Strategies: Field Sales Versus Inside Sales
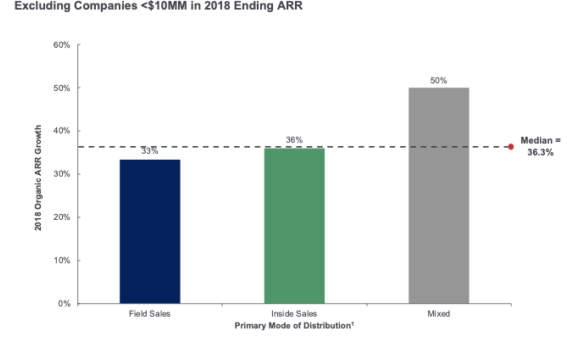
The evolution of go-to-market (GTM) strategies remains one of the most heavily scrutinized areas in the SaaS sector. The survey evaluates primary modes of distribution, categorizing companies based on whether field sales, inside sales, internet sales, or channel partnerships drive the majority of new bookings.
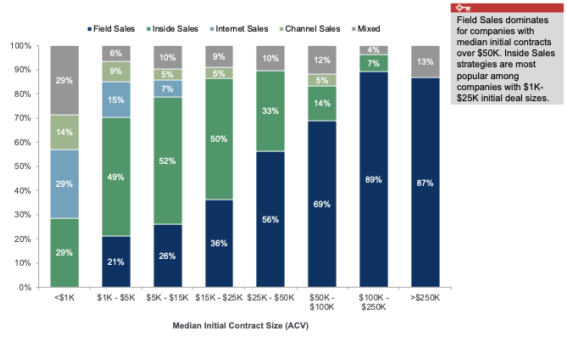
Field sales continue to dominate among companies managing larger enterprise contracts, commanding higher median ARR levels due to complex, high-touch sales cycles. In contrast, inside sales models are predominantly deployed for mid-market and lower-tier enterprise deals, offering a more cost-effective customer acquisition mechanism. The report provides a granular analysis of crossover deal size tiers, comparing the efficacy, CAC ratios, and payback periods of field-dominated versus inside-dominated sales teams.

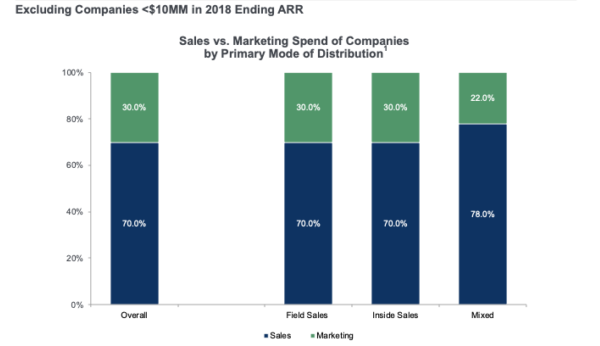
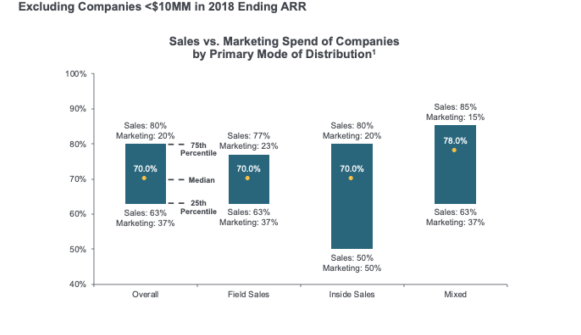
Sales and marketing composition metrics reveal how budget allocations between sales compensation and marketing overhead impact overall efficiency. Marketing expenses—encompassing demand generation, brand positioning, and digital acquisition—work in tandem with sales commissions to fuel new bookings. The survey’s deep dive into commission structures highlights how direct compensation models vary across contract tiers, exploring specific incentives for multi-year deals, renewals, and upsells.
CAC Ratios, Payback Periods, and Capital Efficiency
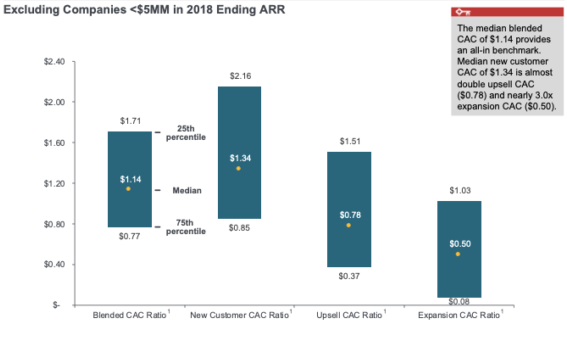
Understanding the true cost of acquiring a customer is critical for determining the long-term viability of a SaaS business model. The 2019 report outlines precise definitions for CAC ratios, distinguishing between blended CAC, new customer acquisition costs, and upsell-related expenditures.
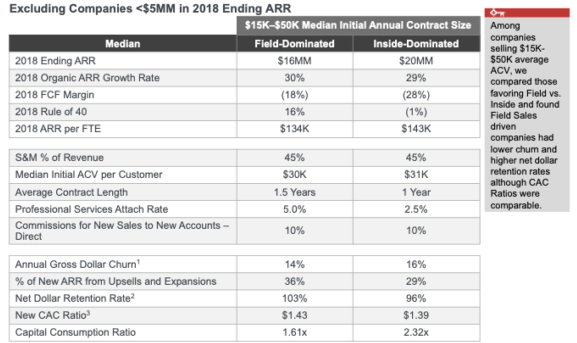
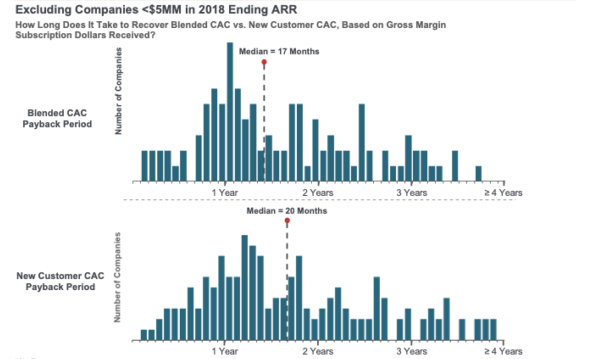
Subscription gross margin serves as the foundational multiplier in calculating implied CAC payback periods. By dividing the CAC ratio by the subscription gross margin, leadership teams can determine the exact number of months required to recover fully-loaded customer acquisition costs through gross profit. The survey data indicates that while elite performers achieve rapid payback periods of under twelve months, the broader median cohort experiences longer horizons, heavily influenced by their primary distribution channel and target market segment.
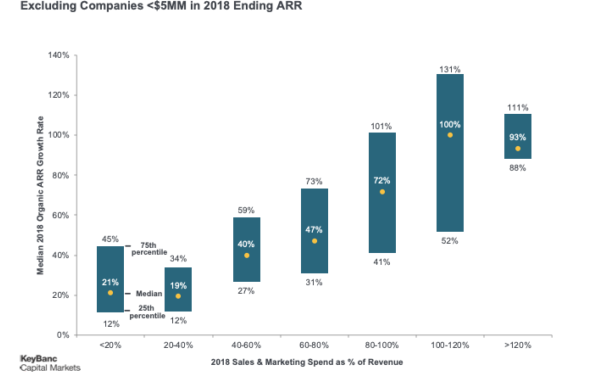
Capital efficiency metrics further contextualize these CAC figures. By evaluating cumulative primary equity raised and debt drawn against net cash positions, the survey demonstrates that capital-efficient SaaS companies achieve sustainable growth without relying on excessive external funding rounds. This efficiency is especially critical in macroeconomic environments where venture capital and private equity deployment cycles fluctuate.
Operational Infrastructure and Delivery Trends
Beyond financial metrics, the survey examines the technical and operational underpinnings of modern SaaS architecture. Subscription gross margins—adjusted to exclude stock-based compensation and inclusive of customer support expenses—remain exceptionally high across the industry, frequently hovering above the 70% to 80% threshold.
A historical review of SaaS application delivery trends reveals a definitive industry migration toward third-party cloud infrastructure providers. Amazon Web Services (AWS) retains a commanding lead as the predominant hosting environment for surveyed companies, followed by Microsoft Azure and Google Cloud Platform. While a minority of early-stage or specialized firms continue to maintain self-managed servers, hybrid and multi-cloud strategies are gaining traction among larger enterprises seeking redundancy and optimization.

Additionally, the report addresses the role of professional services in initial contract structuring. For companies targeting enterprise clients, professional services often account for a notable percentage of first-year ARR, reflecting the complex implementation, customization, and integration requirements associated with enterprise-grade deployments. SMB-focused SaaS providers, by contrast, typically maintain minimal professional services overhead, emphasizing rapid, self-service onboarding.
Implications and Strategic Takeaways for Industry Stakeholders
The publication of the 2019 KBCM Technology Group and forEntrepreneurs survey provides a vital benchmarking toolkit for executives navigating the complexities of the private cloud market. By contrasting individual company performance against median industry standards, management teams can identify operational bottlenecks, optimize sales and marketing expenditures, and refine their go-to-market motions.
As the SaaS landscape matures, the emphasis on disciplined capital allocation and sustainable growth has taken precedence over growth-at-all-costs mentalities. The insights generated by this ongoing research collaboration equip founders and investors with the empirical data necessary to make informed strategic decisions, ensuring that private software companies can scale efficiently in an increasingly competitive global economy. The full report, containing comprehensive data tables and extended analytical commentary, remains accessible via KBCM Technology Group’s official resource library for industry professionals seeking deeper operational guidance.