The Hidden Cost of Modern Living: How Small Financial Shocks Expose Systemic Economic Vulnerability

The transition of children into full-time education marks a significant milestone for many families, often providing a window of opportunity for parents to return to the workforce or pursue professional development. In 2024, one San Francisco family navigated this shift as the wife completed a rigorous six-month teaching credential program through UCLA, subsequently securing a position as a substitute teacher. However, this journey toward financial growth encountered a stark reality: the thin margins of modern household economics, where a single, relatively minor administrative error can negate an entire day of labor.
The Chronology of an Economic Setback
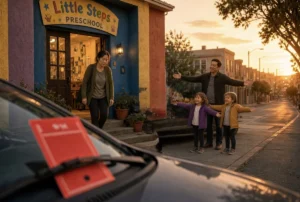
The incident occurred on August 31, 2024, during a routine school pick-up and commute. In an effort to facilitate a family errand—a brief stop at a local bakery—a vehicle was parked in a red zone for approximately three minutes. Despite the driver’s proximity and the presence of other passengers, a parking enforcement officer issued a citation.
The financial impact was initially masked by a breakdown in communication. The citation, which carried a base fine of $108, was misplaced in a garage and remained undiscovered for 62 days. By the time the notice was recovered on September 22, the original deadline of September 21 had passed, triggering a $45 late fee and bringing the total liability to $153. This event highlights a recurring challenge for many households: the compounding effect of late fees and penalties on top of already strained budgets.
Analysis of Labor and Net Take-Home Pay
To understand the severity of this financial shock, one must examine the relationship between gross hourly wages and net disposable income. The educator in this instance earned a gross rate of $26 per hour. In an eight-hour workday, this equates to $208 in gross earnings. When subjected to federal, state, and local tax withholdings—compounded by the household’s existing income level which places them in a higher tax bracket—the take-home pay is reduced to approximately $145.
The $153 penalty, therefore, represented more than the entirety of the spouse’s daily net income. This phenomenon, often referred to as "financial leakage," illustrates how unexpected costs can effectively render a day of employment net-negative. For households operating on tight budgets, this is not merely an inconvenience; it is a structural barrier to wealth accumulation. According to data from the Federal Reserve’s "Report on the Economic Well-Being of U.S. Households," nearly 37% of adults would struggle to cover an unexpected $400 emergency expense without borrowing money or selling assets. The $153 fine in this scenario sits squarely within the range of expenses that can disrupt the financial stability of the average American family.
The Psychological and Macroeconomic Context
The concept of "financial despair" in this context is defined not by poverty, but by the sense of helplessness that arises when individual agency is eroded by systemic rigidity. Economists note that when a significant portion of a household’s income is eroded by taxes, fees, and the rising cost of living, the incentive structure for labor changes.
Historical context provides a frame of reference for this feeling. During the 2008–2009 financial crisis, many individuals experienced a systemic shock where personal effort—such as maintaining high productivity or fiscal responsibility—offered no protection against market-wide volatility. Today, that same sensation is often triggered by "micro-shocks": medical co-pays, administrative fines, or sudden shifts in municipal tax policy. These events serve as a reminder that for many, the gap between earnings and keepings is narrowing, leading to a phenomenon where the rules of the financial system appear to favor stagnation over progress.
Regulatory and Municipal Implications
The issuance of the fine and the subsequent late fee reflect the rigid nature of municipal parking enforcement in urban centers like San Francisco. From the perspective of city governance, strict enforcement is intended to manage traffic flow, ensure public safety, and generate revenue for public infrastructure. However, the lack of discretion afforded to enforcement officers—even when drivers are present and capable of moving vehicles immediately—often results in friction between residents and municipal authorities.
Residents in high-tax jurisdictions often express a disconnect between the taxes paid and the services received. In San Francisco, the 311 system serves as the primary interface for citizens to report issues such as potholes, illegal dumping, and public nuisance. Increasingly, taxpayers are utilizing these platforms to reclaim value for their tax dollars. While this does not offset individual fines, it represents a shift in civic engagement where citizens are more actively holding municipal services accountable for maintenance and infrastructure quality.
Strategic Responses to Financial Volatility
To mitigate the impact of such financial shocks, financial professionals emphasize the necessity of "financial buffers." These are distinct from emergency savings; they are operational margins built into a monthly budget to absorb the costs of "life friction."
- Calculating the True Hourly Rate: Experts suggest that workers calculate their real hourly rate by including not just their wage, but the cost of commuting, professional attire, childcare, and the mental load of the role. When labor is viewed through this lens, the true cost of a $153 fine becomes apparent: it is not just dollars lost, but hours of life spent in service of a municipal penalty.
- Technological Oversight: Digital tools that provide a comprehensive view of all financial obligations—including bank balances, upcoming payments, and potential late fees—are essential. Platforms that aggregate financial data allow households to identify "leaks" in their budget before they escalate into penalties.
- Behavioral Adjustments: The most effective response to unexpected financial losses is often a modification of daily habits. For instance, eliminating minor, non-essential expenditures that previously felt trivial can create a safety margin that prevents a single incident from causing significant distress.
Broader Societal Perspectives
The experience of this family is emblematic of a wider segment of the population that is "doing everything right"—working full-time, pursuing career advancement, and managing family responsibilities—yet still feeling the pressure of a system that can be unforgiving of minor errors. The systemic nature of these challenges suggests that individual discipline, while necessary, is often insufficient without a broader understanding of the economic environment.
The path toward financial stability, therefore, requires a two-pronged approach. On an individual level, it requires extreme vigilance in tracking expenditures and building robust financial buffers. On a societal level, it demands a conversation about the cumulative burden of fines, fees, and tax structures on the working population. As living costs continue to climb in urban environments, the margin for error for middle-class families continues to shrink.
Ultimately, while the $153 fine was a source of frustration, it served as a catalyst for a re-evaluation of household financial habits. By shifting the focus from the immediate loss to the long-term lesson, the individuals involved were able to identify areas for increased efficiency and reduced risk. This cycle of shock and adaptation is a fundamental component of financial literacy, illustrating that even in the face of systemic financial pressure, individual control over habits and responses remains the most powerful tool for achieving long-term economic independence.
The lesson is clear: in an era of thin margins, the ability to anticipate and avoid the "random" costs of modern life is just as critical as the ability to earn income. As the family continues to navigate their professional journey, the $153 serves as a permanent reminder of the value of their time and the necessity of constant, proactive financial management.