Why It Is Easier To Achieve Financial Independence And Retire Early At 35 Than At 50

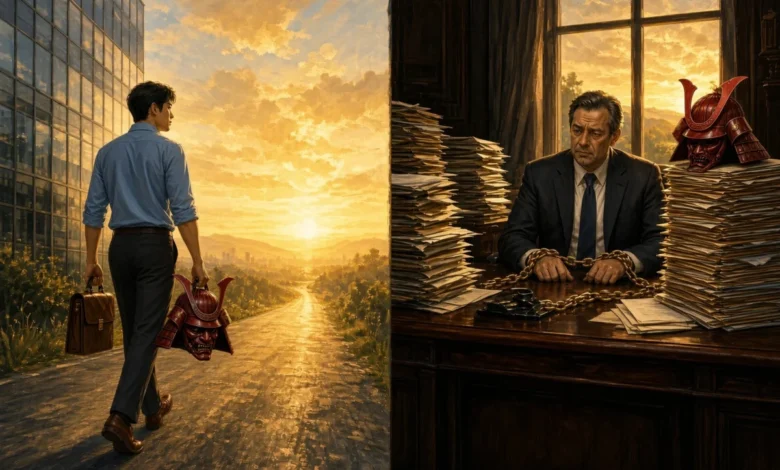
The concept of Financial Independence, Retire Early (FIRE) has transitioned from a fringe movement to a mainstream financial aspiration. While conventional wisdom often suggests that waiting until age 50 provides a more stable foundation for retirement due to increased capital accumulation, recent analysis of career trajectories and economic data suggests the opposite. Achieving financial independence at 35, while perceived as inherently riskier, often presents fewer structural and psychological barriers than attempting the same transition at 50.
The Mechanics of Early Retirement: A Chronological Comparison
The distinction between retiring at 35 versus 50 involves more than just a 15-year difference in age; it involves a fundamental shift in risk exposure, lifestyle obligations, and labor market mobility.
For a professional in their mid-30s, the path to FIRE is typically defined by a decade or more of aggressive saving, often exceeding 50% of annual income. At this stage, the individual is usually in the early-to-mid phases of their career. While the loss of future earnings is significant, the individual generally lacks the heavy financial burdens that characterize the later stages of life, such as private school tuition, high-end real estate debt, and the potential need to fund aging parents’ elder care.
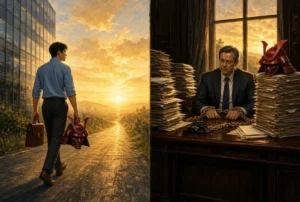
Conversely, by age 50, a professional has often ascended to senior leadership roles—such as Managing Director or Executive Vice President. In these positions, compensation packages become increasingly complex, featuring deferred bonuses, equity grants, and stock options. The opportunity cost of walking away from these "golden handcuffs" is exponentially higher than that of a mid-career professional.
Supporting Data and Economic Context
The economic landscape for the two age groups reveals a stark contrast in flexibility. A 35-year-old worker who chooses to leave the workforce generally retains high labor market utility. Recruiters and hiring managers view a 35-year-old with 13 years of experience as highly employable, often capable of re-entering the workforce within a 12-month window should their early retirement experiment fail.
In contrast, the job market for individuals approaching 50 is increasingly constrained. Structural shifts in the labor market, compounded by the rise of artificial intelligence and automation, have reduced the demand for mid-to-senior level knowledge workers in certain sectors. Data indicates that professionals over 50 face longer periods of unemployment when seeking new roles compared to their younger counterparts. Furthermore, the "age penalty" in salary negotiations often results in a lower compensation ceiling for those re-entering the workforce later in life.
Lifestyle Inflation and the Burden of Obligation
The phenomenon of lifestyle inflation acts as a primary inhibitor to retirement for those in their 40s and 50s. As income rises over a two-decade career, household expenditures—housing, education, and service-based living—tend to adjust upward.

A report on household financial planning suggests that by age 50, the average high-earning household has committed to a standard of living that requires a consistent, high-level W-2 income to sustain. This creates a psychological and financial trap: the individual is no longer just working for themselves, but for a complex ecosystem of dependents and fixed costs. When the cost of maintaining this lifestyle reaches its zenith, the decision to retire requires a significantly larger net worth to offset the loss of active income, effectively pushing the "safe" retirement age further into the future.
Comparative Risk Profile
| Variable | Financial Independence at 35 | Financial Independence at 50 |
|---|---|---|
| Opportunity Cost | Moderate (Early Career) | High (Peak Earning Years) |
| Re-employment Risk | Low (High Marketability) | High (Ageism & AI Disruption) |
| Fixed Obligations | Minimal | Substantial (Tuition, Mortgages) |
| Regret Potential | High flexibility to pivot | Low; lost high-earning capacity |
| Market Volatility Exposure | High (Longer drawdown period) | Lower (Shorter timeline to RMDs) |
Professional Perspectives on Career Transitions
Career counselors and organizational psychologists observe that the "leap" at 35 is frequently fueled by a desire for autonomy, whereas the potential transition at 50 is often viewed through the lens of risk mitigation.
"When an individual reaches the age of 50, the decision to exit the workforce is often treated as a finality," notes one executive search consultant. "At 35, there is a perception of a ‘safety net’—the idea that if the retirement plan fails, there is time to build back. At 50, the fear of permanent loss of income or status often leads to decision paralysis, where the professional stays in a role they dislike for a decade longer than necessary."
This sentiment is echoed by those who have successfully navigated the transition. Case studies of former financial sector employees show that those who exited in their early 30s were more likely to successfully pivot to entrepreneurship or alternative careers. Those who waited until their late 40s reported higher levels of anxiety regarding their "exit strategy," often requiring a more rigorous, years-long negotiation of severance or early retirement packages to feel secure enough to depart.
The Impact of Modern Economic Pressures
The broader implication for the modern workforce is that the traditional "retirement at 65" model is being challenged by two opposing forces: the desire for personal autonomy and the rising cost of middle-class stability.
For parents, the pressure to fund higher education—with some private universities projecting costs exceeding $160,000 annually by the late 2030s—is a significant anchor. This reality forces many to continue working well beyond their desired retirement date. The implication is that the "golden handcuffs" are not merely psychological; they are tied to the macro-economic realities of the current education and housing markets.
Conclusion and Future Implications
The evidence suggests that the optimal window for early retirement is often found before an individual reaches the peak of their earning potential and the zenith of their personal obligations. While the prospect of retiring at 35 is objectively terrifying due to the long-term uncertainty it presents, it is statistically more manageable than the complexities involved in retiring at 50.
For those currently contemplating an exit, the recommendation from analysts is to prioritize the negotiation of severance and the consolidation of assets well before reaching the peak of one’s career. By engineering a departure earlier, individuals may preserve their long-term professional flexibility and reduce the compounding weight of lifestyle inflation. Ultimately, the transition to financial independence is not a matter of reaching a specific, safe number, but of managing the trade-off between the security of a paycheck and the volatility of personal freedom. As the labor market continues to evolve, the ability to act early remains a significant advantage for those seeking to decouple their livelihood from traditional employment structures.