The State of the SaaS Industry: A Comprehensive Analysis of 2016 Market Trends and Growth Strategies

The year 2016 marked a watershed moment for the Software as a Service (SaaS) industry, characterized by an unprecedented democratization of specialized operational knowledge and a fundamental shift in how businesses scale. As the industry matured, the barriers to entry lowered significantly, leading to a crowded marketplace that forced companies to pivot away from traditional, volume-based growth models toward brand-centric, customer-focused strategies. This transition, documented extensively by industry leaders and venture capitalists throughout the year, defined a new era of "knowledge-sharing" where the proprietary secrets of rapid scaling became public discourse.
A Decade of Evolution: From Product-Market Fit to Market Saturation
To understand the landscape of 2016, one must look at the preceding decade. In the early 2000s and early 2010s, a SaaS company could achieve significant growth through aggressive sales and marketing execution, often ahead of securing true product-market fit. By 2016, however, the proliferation of low-code development tools and the rise of the "API economy" made it easier than ever for competitors to enter any given niche.
Data from the period indicated that while reaching the $1 million to $2 million Annual Recurring Revenue (ARR) milestone had become more accessible, the "chasm" between $2 million and $10 million in ARR widened. Industry analysts, such as Christoph Janz of Point Nine Capital, noted that the tactical playbook for early-stage growth no longer sufficed for the mid-market stage. Companies were forced to reconsider their "animal hunting" strategy—a framework used to define customer acquisition based on the size of the prospect—ensuring that their pricing models and marketing channels were perfectly aligned with their target demographic, whether they were small and medium-sized businesses (SMBs) or enterprise-grade accounts.
The Shift Toward Customer-Centric Operations
As the market became saturated with similar feature sets, the primary differentiator for successful SaaS firms in 2016 shifted from technical functionality to the "service" component of the software. This period saw a decline in the effectiveness of cold-outreach marketing and a surge in the importance of Customer Success (CS) departments.
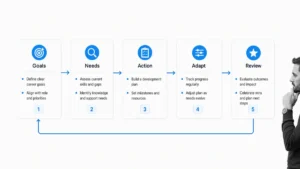
The philosophy, championed by leaders like David Cancel, was that the most "remarkable" SaaS CEOs were those who embedded a customer-driven culture into the DNA of their organizations. Instead of relying solely on sales teams to drive revenue, companies began utilizing automated, low-touch customer success workflows. Tactics included the implementation of targeted drip email campaigns that nudged users toward upgrades based on usage patterns rather than arbitrary sales cycles. By mapping the customer journey—as demonstrated by firms like Lucidchart—organizations were able to generate thousands of leads by simply listening to existing user support interactions, effectively turning cost centers (support) into revenue engines.
The Rise of the Bootstrapped and Niche SaaS Model
While venture-backed firms dominated the headlines, 2016 also saw a significant surge in self-funded, or "bootstrapped," SaaS businesses. The lower cost of cloud infrastructure and the availability of sophisticated marketing automation tools allowed solo developers and small teams to build "picks and shovels" for highly specific industry needs.
The economic implications were substantial. Reports from communities like Hacker News and analyses of platforms like ConvertKit highlighted a trend where profitability became a primary objective rather than a secondary concern. For instance, ConvertKit’s shift toward a 51% profit margin over a five-month period in 2016 served as a case study for the industry, proving that focusing on unit economics could lead to sustainable growth without the need for dilutive equity financing. This period established that self-funded entities were often more operationally efficient than their venture-backed counterparts, primarily because they were forced to optimize their acquisition costs and churn rates from day one to ensure survival.
Democratization of Technical Knowledge and Metrics
A defining feature of the 2016 SaaS environment was the public sharing of internal metrics. Leaders from companies like Buffer, BuzzSumo, and various emerging startups began publishing detailed accounts of their growth, including MRR (Monthly Recurring Revenue), churn, and customer acquisition costs (CAC).
This trend was further bolstered by the creation of standardized spreadsheets and open-source frameworks for SaaS accounting. When industry experts such as David Cummings and Ash Read published templates for tracking growth, they effectively lowered the barrier for non-technical founders to understand the health of their businesses. This transparency did more than help individual companies; it created a shared language for the industry, allowing for more accurate valuations of SaaS businesses. Firms like FE International, which specialized in the acquisition of small-scale SaaS entities, utilized this increased data availability to create more robust methodologies for pricing businesses, reflecting a professionalization of the entire secondary market for software companies.
Future Projections and Industry Disruption
By the end of 2016, industry observers began to look beyond the current SaaS model, questioning whether the industry itself was ripe for disruption. Analysts like Justin Jackson and Tomasz Tunguz posited that the next wave of innovation would not come from simply building another tool, but from creating deeper, intelligence-driven insights from the data generated by those tools.
The consensus among industry leaders at the close of 2016 was that the "easy growth" era had concluded. To remain competitive in 2017 and beyond, SaaS providers would need to focus on three core pillars:
- Vertical Specialization: Abandoning generalist software in favor of tools that solved specific, complex workflows for niche industries.
- Predictive Analytics: Leveraging user engagement data to anticipate needs before the customer requested them, thereby reducing churn.
- Operational Efficiency: Maintaining lean teams while scaling, a lesson learned from the successful bootstrapped ventures of the year.
Conclusion and Broader Implications
The events of 2016 served as a maturation point for the SaaS industry. The transition from a gold-rush mentality to a focus on sustainable, customer-centric growth established the foundations for the current SaaS landscape. Companies that survived this period were those that understood that software was no longer just a product, but a continuous service relationship.
The increased availability of data, the focus on profitability, and the prioritization of brand over sheer marketing volume have become the standard operating procedures for modern technology firms. As the market continues to evolve, the lessons from this pivotal year—most notably that business intelligence and customer empathy are the ultimate competitive advantages—remain as relevant today as they were when they were first documented. The era of information asymmetry in SaaS has largely ended, replaced by an ecosystem where the most successful companies are those that best synthesize the wealth of available knowledge into actionable, customer-focused strategies.
Related posts: