The concept of Financial Independence, Retire Early (FIRE) is frequently framed as a linear progression of wealth accumulation. Conventional wisdom suggests that as an individual nears their peak earning years, the transition into retirement becomes progressively easier. However, recent data and career-path analysis suggest that the opposite may be true: the "golden handcuffs" of high-level professional roles, combined with escalating lifestyle inflation and shifting economic landscapes, make the transition to early retirement significantly more difficult as a worker ages.
The Anatomy of the Mid-Career Exit
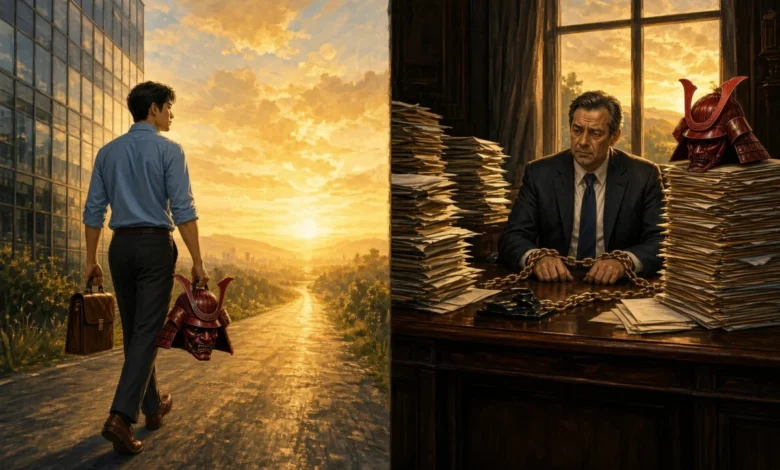
In 2012, a significant shift in personal finance culture began to gain traction when professionals in high-stress sectors—most notably investment banking—began opting out of the traditional career trajectory long before the standard retirement age. For those in their mid-30s, the decision to retire is often characterized by a high degree of adaptability. At 35, an individual typically possesses fewer dependents, lower baseline expenses, and a job market that still views them as a prime candidate for recruitment should their exit strategy falter.
Conversely, the professional profile of a 50-year-old in a high-earning sector, such as investment banking or big tech, presents a different set of variables. By age 50, a Managing Director or a senior technical lead may command a compensation package exceeding $2.5 million annually when base salary, performance bonuses, and deferred compensation are aggregated. The psychological and financial burden of abandoning such a figure creates an inertia that is difficult to overcome.
Chronology of Economic Entrapment
The progression toward "trapped" wealth typically follows a predictable timeline:
- Age 22–30: The Accumulation Phase. High savings rates—often exceeding 50% of income—are possible due to a lack of significant family obligations and a relatively low cost of living.
- Age 30–40: The Pivot Point. Professionals reach a stage where they have achieved enough financial security to potentially retire. During this decade, the risk of "failure" is mitigated by the ability to re-enter the workforce within a 12-to-24-month window.
- Age 40–50: The Expansion Phase. Lifestyle inflation accelerates. This often includes the purchase of a larger primary residence, private school tuition for children, and the assumption of caregiving duties for aging parents.
- Age 50+: The Lock-in. The cost of maintaining a high-net-worth lifestyle requires sustained, high-level income. Simultaneously, labor market data indicates that hiring demand for workers over 50 in certain sectors is lower than for their younger counterparts, particularly as artificial intelligence begins to automate entry- and mid-level knowledge tasks.
Supporting Data and Market Realities
The difficulty of exiting the workforce at 50 is not merely a matter of personal preference but a reflection of macro-economic pressures. According to recent labor market studies, the "shelf life" of technical and high-finance skills has compressed. As AI tools increase the efficiency of junior and mid-level employees, the necessity for a high-cost, senior-level individual contributor diminishes.
Furthermore, the "cost of living" for a 50-year-old is statistically higher than that of a 35-year-old. When accounting for university tuition, which is projected to see significant inflationary pressure, and the rising costs of private elder care, the amount of liquid capital required to retire comfortably has increased. For a 50-year-old, the financial model must sustain a household for at least 30 to 35 years, whereas a 35-year-old has a 50-year horizon, but also a significantly higher probability of successfully returning to the labor market to bolster their assets if necessary.
The Role of Lifestyle Inflation
A critical factor often overlooked in retirement planning is the role of "lifestyle creep." As an individual’s annual compensation scales from $150,000 to $500,000 and beyond, discretionary spending often expands to fill the available income. This includes, but is not limited to, domestic staff, luxury travel, and real estate upgrades.
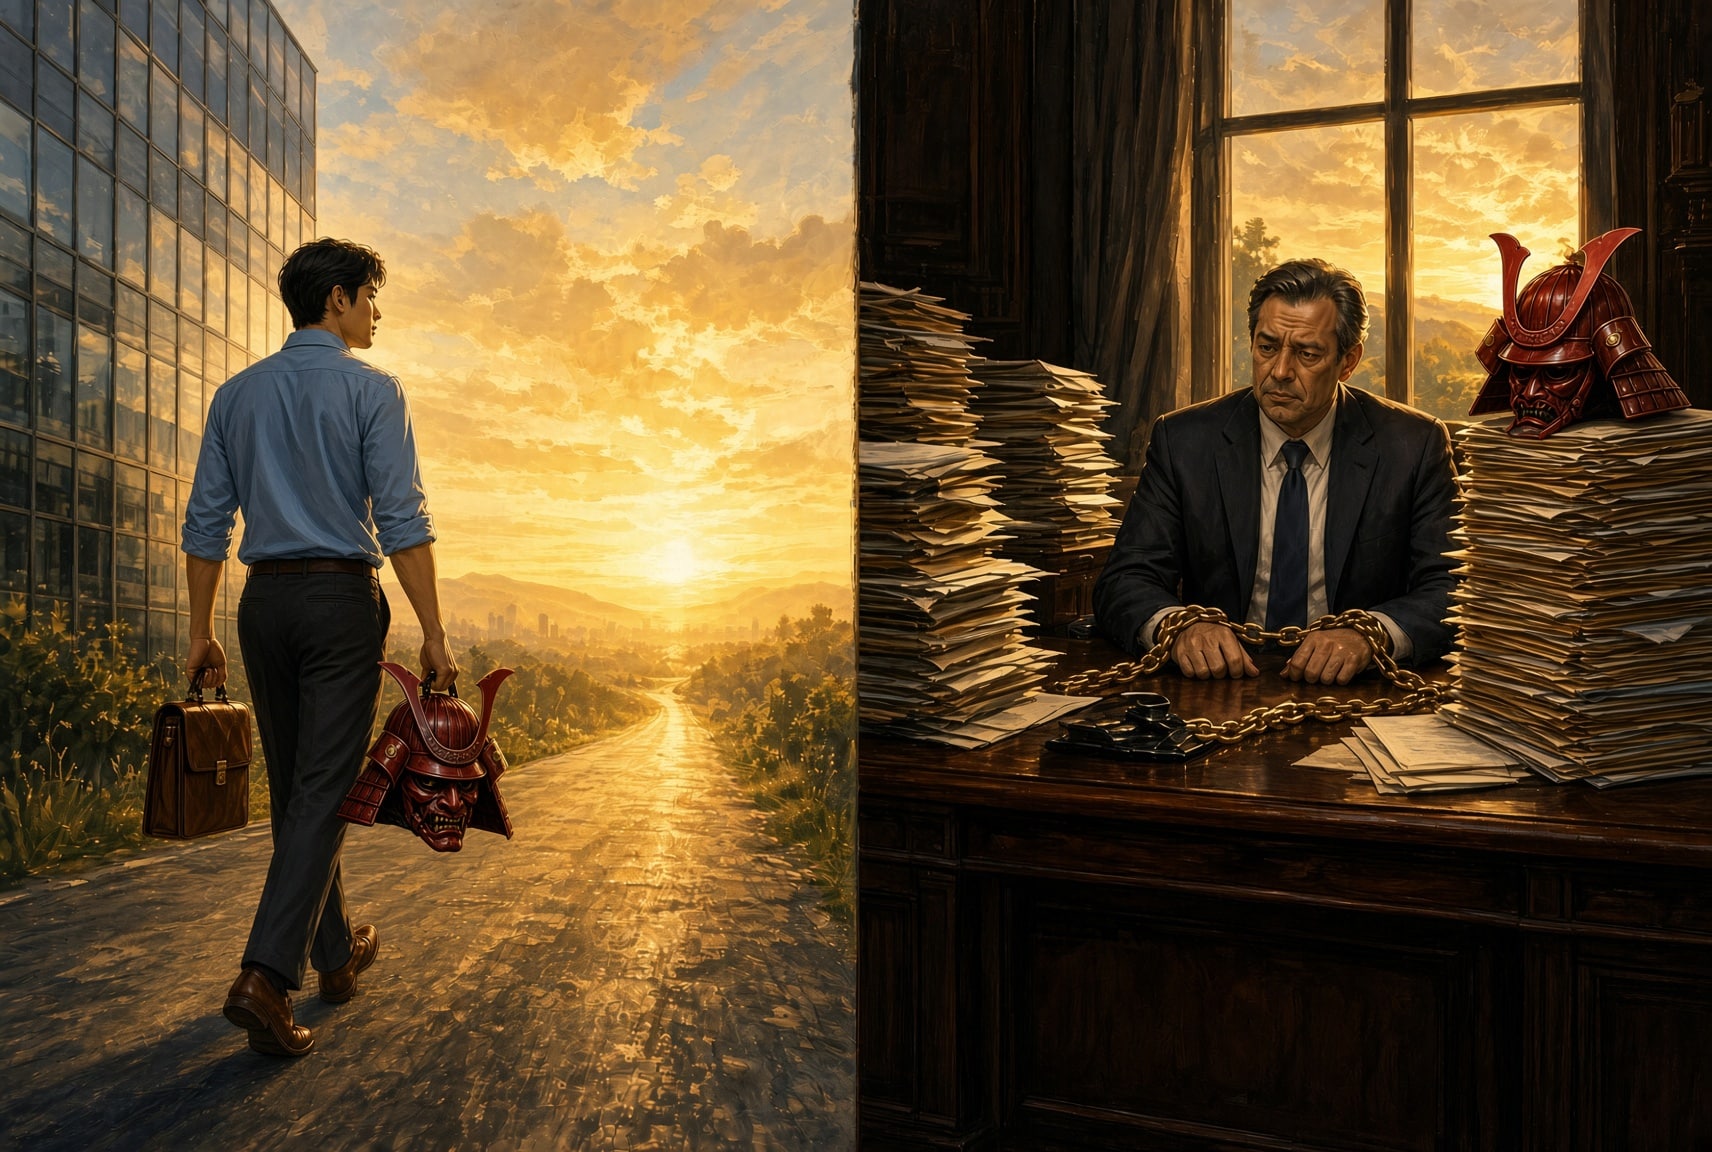
Once this lifestyle is established, it becomes a fixed cost. The individual is no longer working solely for survival; they are working to maintain a specific standard of living for their family. This creates a feedback loop: the higher the lifestyle cost, the more "essential" the job becomes, and the less likely the individual is to risk a transition to early retirement.
Comparative Analysis: Age 35 vs. Age 50
| Metric | Retiring at 35 | Retiring at 50 |
|---|---|---|
| Annual Compensation | ~$150,000 | ~$350,000+ |
| Dependents | Minimal | High (Spouse, Kids, Parents) |
| Market Re-entry | High Probability | Low Probability |
| Lifestyle Inflation | Minimal | Fully Baked In |
| Financial Runway | 50+ Years | 35+ Years |
| Psychological Barrier | Manageable | Extremely High |
Institutional Responses and Professional Pivot Strategies
In response to the increasing desire for autonomy, many professionals are turning toward "engineered layoffs." Rather than resigning, which forfeits severance packages and potential unemployment benefits, employees are increasingly negotiating exit terms that include comprehensive severance, accelerated vesting of equity, and health coverage.
Financial advisors note that the shift from an active W-2 income to a portfolio-dependent lifestyle requires a rigorous audit of fixed versus variable expenses. For those in their 40s considering an exit, the consensus among wealth management professionals is to conduct a "sabbatical test." By taking a three-month leave of absence, professionals can determine if their financial model is sustainable and if they are psychologically prepared for the loss of professional identity that often accompanies retirement.
The Impact of Emerging Technologies
The rise of artificial intelligence has introduced a new variable into the retirement equation. The traditional path of "grinding" for 30 years to ensure generational wealth is being challenged by the potential for job displacement. Some experts argue that if the future of work is uncertain due to automation, the incentive to stay in a traditional role may diminish, as the job security that was once a trade-off for long hours is no longer guaranteed.
Conversely, others argue that this uncertainty makes the need for a massive capital buffer even more urgent. The paradox of the modern FIRE movement is that the very environment that encourages people to save—a volatile and competitive economy—is the same environment that makes the act of retiring early feel like a dangerous gamble.
Conclusion: The Window of Opportunity
The evidence suggests that the "window" for early retirement is narrower than previously assumed. By the time a professional reaches their 50th year, the structural and financial barriers to leaving the workforce often become insurmountable. The decision to retire at 35 is an act of calculated risk-taking, supported by the resilience of youth and the flexibility of the labor market. The decision to retire at 50, however, is a much more rigid undertaking that requires a level of absolute financial certainty that few can truly achieve.
For those contemplating an early exit, the data suggests that waiting for the "perfect" time—or for a sense of total safety—is a strategy that often leads to indefinite employment. The most viable path appears to be the one taken while the individual still possesses the capacity to adapt, recover, and pivot should their initial retirement strategy face unforeseen economic headwinds. As the workforce continues to evolve, the distinction between "early retirement" and "retirement" will likely be defined by the age at which an individual realizes that the risk of staying in a career has finally surpassed the risk of leaving it.