In 2024, as families across the United States navigated the transition of children into full-time primary education, many households experienced a significant shift in domestic time management. For a San Francisco-based couple, this transition offered a newfound window of opportunity, allowing for career pivots and professional development. However, a routine incident involving a municipal parking citation serves as a case study for the fragile financial equilibrium that many middle-class families maintain in high-cost-of-living urban centers. This event highlights how minor administrative oversights, when compounded by late fees and tax structures, can significantly impact a household’s net income.
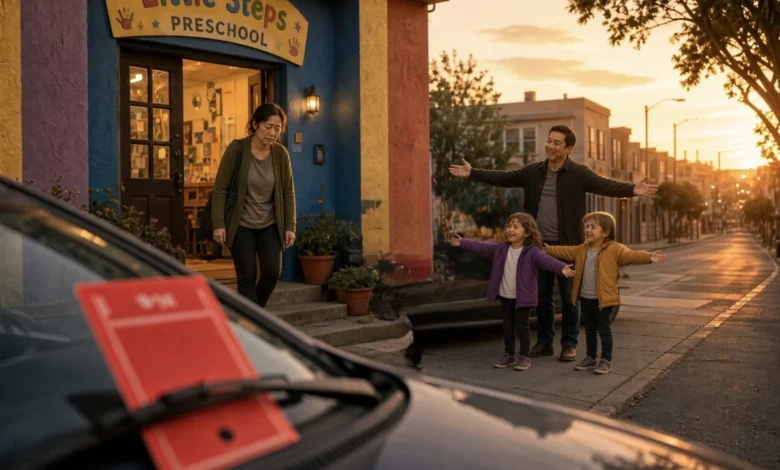
The incident occurred during a routine evening pickup. After completing a day of substitute teaching at a local preschool—a role pursued to gain experience for a long-term career transition into education—a woman was picked up by her spouse. To facilitate a quick stop at a local bakery, the vehicle was parked in a restricted zone. Despite the duration of the stop being approximately three minutes, the vehicle was issued a parking citation. The intersection of this administrative penalty and the realities of modern wage labor provides a stark look at how thin the margins have become for working families.
Chronology of the Incident and Fiscal Impact
The timeline of the citation illustrates the dangers of bureaucratic delays. On August 31, the vehicle was ticketed in San Francisco. A standard municipal parking fine in the city typically ranges from $80 to $110 depending on the violation. In this instance, the initial fine was $108. The due date for payment was set for September 21.
Due to a miscommunication and the physical placement of the citation within the home, the notice remained undiscovered for 62 days. It was not until September 22 that the fine was identified, by which time a $45 late fee had been applied, bringing the total financial obligation to $153.
The economic implications are best understood through the lens of the spouse’s daily earnings. As a substitute teacher, the individual earned a gross wage of $26 per hour. Over an eight-hour shift, this resulted in $208 in gross income. After accounting for federal and state tax withholdings, which are elevated for households with secondary streams of income such as passive investments, the net take-home pay was approximately $145. Consequently, the $153 penalty represented more than the entirety of a full day’s labor. This phenomenon, often referred to as "financial leakage," illustrates how quickly the gains of professional effort can be erased by unexpected municipal or administrative costs.
The Macro Context: Financial Despair in High-Cost Environments
The term "financial despair" is increasingly utilized by economists to describe the psychological and fiscal state of individuals who are meeting all their obligations—working full-time, paying taxes, and managing debt—yet remain one minor incident away from a significant budgetary deficit. Data from the Federal Reserve’s "Report on the Economic Well-Being of U.S. Households" consistently indicates that a substantial portion of Americans would struggle to cover a $400 emergency expense without borrowing or selling assets.
In cities like San Francisco, where the cost of living index significantly exceeds the national average, the "rigged" feeling often cited by residents is rooted in the interplay between high marginal tax rates and the lack of elasticity in household budgets. When a family is operating on thin margins, the loss of $153 is not merely an inconvenience; it represents a tangible reduction in capital available for essential goods, such as food or utility payments.
Historically, periods of economic volatility—such as the 2008 financial crisis—have served as catalysts for significant shifts in personal finance behaviors. For many professionals who entered the workforce during that period, the experience of watching net worths decline due to external market forces created a permanent shift toward building "financial buffers." This defensive posture—prioritizing savings and liquidity—has become the standard defense mechanism against the inherent unpredictability of the modern economy.
Administrative Recourse and Municipal Engagement
The frustration surrounding the ticket is compounded by the perceived lack of return on tax investments. Residents in major metropolitan areas often cite a disconnect between the high taxes paid and the quality of public services received. The use of municipal systems, such as the 311 service in San Francisco, represents an effort by citizens to hold local government accountable for infrastructure maintenance.
The 311 system allows residents to report a variety of issues, including:
- Street and Sidewalk Maintenance: Reporting potholes, cracked pavement, and debris.
- Waste and Public Nuisance: Managing illegal dumping, overflowing public trash receptacles, and graffiti.
- Infrastructure: Issues with tree maintenance, park degradation, and street lighting.
By engaging with these systems, citizens attempt to rebalance the "value proposition" of their tax contributions. The incident described serves as a reminder that financial literacy includes not only tracking personal spending but also utilizing the services for which one is paying through municipal taxation.
Analysis: Calculating the Real Hourly Rate
Financial analysts frequently advise individuals to calculate their "true" hourly rate to better understand the cost-benefit analysis of their time. This calculation goes beyond the gross wage listed on a pay stub. It requires a comprehensive audit of:
- Commute Time: The total time spent traveling to and from the workplace.
- Prep and Decompression: The mental and physical time required to prepare for work and the "recovery" time required afterward.
- Ancillary Expenses: Costs associated with working, such as professional attire, transit fees, and child care.
When the take-home pay is divided by these total hours, the effective hourly rate is often significantly lower than the nominal rate. For a worker earning $26 per hour, the inclusion of commute and preparation time might reduce that effective rate to closer to $15 or $18. This reality makes the impact of a $153 fine even more severe, as it equates to nearly two full days of productive life being traded for a parking error.
Strategies for Financial Stability
To mitigate the impact of unexpected financial shocks, experts recommend several proactive measures:
- Comprehensive Financial Tracking: Utilizing digital tools to aggregate all financial accounts ensures that unexpected bills, such as tax assessments or municipal fines, are captured in real-time before late fees accrue.
- The Buffer Principle: Maintaining a dedicated emergency fund specifically for non-negotiable expenses—such as medical co-pays, home repairs, or unexpected municipal penalties—prevents these events from disrupting the household’s long-term investment strategy.
- Professional Consultation: For households with investable assets exceeding $100,000, engaging with a licensed financial professional can provide a structured roadmap. Such consultations are often available at no cost through major financial management platforms and can identify structural inefficiencies in a family’s financial plan.
Conclusion
While the $153 parking citation may appear to be a trivial matter in the grand scale of national economics, it functions as a potent metaphor for the precariousness of modern middle-class life. The event underscores the necessity of constant vigilance in personal financial management. For the individuals involved, the experience has prompted a shift in daily logistics—opting for direct transit and reducing exposure to potential risks—and a renewed focus on fiscal discipline.
Financial despair, while debilitating in the short term, often acts as a pivot point for long-term behavioral change. By recognizing the true cost of time and the hidden inefficiencies within the system, households can move from a reactive state to a proactive one, effectively building the buffers necessary to withstand the inevitable disruptions of the modern economy. In this light, even a costly administrative error can be transformed into a valuable lesson in financial resilience.