Stripe Data Reveals How Artificial Intelligence Startups are Shattering Traditional Business Growth Models

The modern technology startup ecosystem is undergoing a fundamental structural transformation, characterized by hyper-acceleration, compressed go-to-market timelines, and unprecedented global reach. According to proprietary transaction and revenue data compiled by Stripe—which processes payments for a significant majority of the world’s fastest-growing artificial intelligence enterprises—AI companies are defying decades-old norms of business software growth.
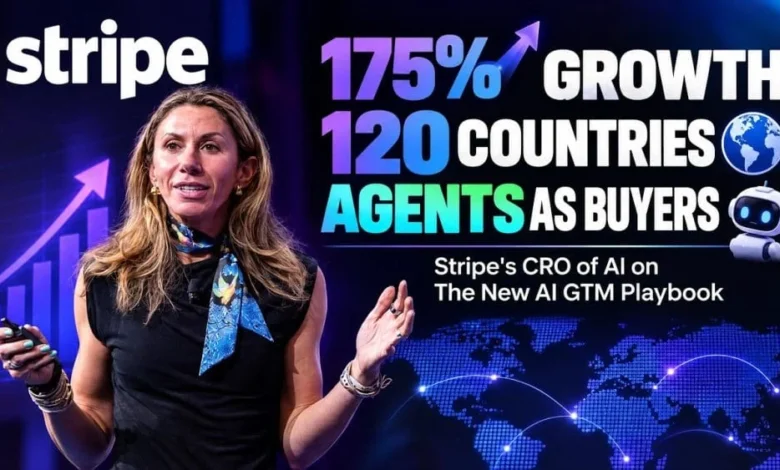
During a detailed presentation at the recent SaaStr AI session, Maia Josebachvili, Chief Revenue Officer of AI at Stripe and former enterprise general manager, outlined the staggering metrics defining the current cohort of artificial intelligence ventures. Josebachvili, who previously co-founded adventure travel company Urban Escapes (subsequently acquired by LivingSocial) and served as a founding team member at Greenhouse through its billion-dollar acquisition, contrasted her early entrepreneurial experiences with the hyper-speed landscape navigated by modern founders.
By analyzing the transactional activity of thousands of businesses and millions of consumers utilizing Stripe infrastructure, the payments giant has mapped a new macroeconomic reality. The data indicates that traditional sequential business growth—historically categorized by localized market dominance, delayed international expansion, and gradual layering of enterprise sales teams—has been compressed into a simultaneous, parallel execution model operating from day one.
Unprecedented Growth Trajectories Defy SaaS Decayed Curves
In the traditional software-as-a-service (SaaS) and B2B sectors, growth rates invariably decay as companies scale. Expanding from a low baseline naturally yields triple-digit percentages, but maintaining or accelerating those rates at scale has historically been considered an impossibility. Stripe’s cohort data highlights an extraordinary anomaly among top-tier artificial intelligence companies, whose year-over-year growth rates accelerated rather than slowed down.
According to Stripe’s ledger data, the company’s top-performing AI customer cohort achieved an average growth rate of 120% in 2025, which further surged to 175% in 2026. This dynamic translates to nearly tripling business revenue within a single calendar year at a scale previously unseen in corporate history.
This enterprise momentum is mirrored in consumer adoption patterns. Metrics captured via Stripe’s Link payment network demonstrate that the absolute number of individual consumers purchasing AI-related products doubled within a twelve-month window, expanding from under 6 million to 14 million users globally. Furthermore, top-tier Link buyers now allocate an average of $371 annually toward artificial intelligence products—a notable increase from $140 the previous year. This expenditure level now surpasses the average American consumer’s combined annual spending on traditional household utilities such as dedicated internet access, television streaming subscriptions, and mobile phone services.
The Six-Week Genesis: Idea to Revenue Compression
The friction associated with launching a digital commerce enterprise has historically constrained the velocity of technological innovation. Reflecting on her entrepreneurial origins, Josebachvili noted that building a functional online checkout system during the founding of Urban Escapes required such complex engineering and merchant acquisition hurdles that initial customers were instructed to mail physical paper checks to her Brooklyn apartment—a manual workaround that clients routinely executed.
Today, the integration of embedded payments within modern developer platforms such as Replit and Vercel has fundamentally altered this timeline. Stripe’s telemetry indicates that each successive monthly cohort of developers successfully transitions from an initial software concept to their first charged customer at an accelerating pace, with the current average benchmark dropping below six weeks.
Simultaneously, ecosystem indicators track closely with this code-to-cash velocity. Following the mainstream adoption of agentic coding utilities, iOS application releases surged by 24% month-over-month across development platforms, while corporate entity formations, measured by Delaware incorporations, tracked an identical upward curve.
A critical demographic shift has accompanied this acceleration. While initial industry speculation suggested that AI coding assistants would primarily democratize software creation for non-technical entrepreneurs, empirical payment and usage data reveals a different reality. The proportion of technical founders in new venture cohorts has increased by seven percentage points year-over-year. Rather than replacing technical talent, generative coding tools have empowered experienced engineers to accomplish development milestones in mere days that previously required dedicated engineering departments months to execute.
Hyper-Internationalization and Day-One Global Markets
The traditional playbook for international expansion dictated that a technology company should concentrate exclusively on its domestic market, achieve sustained product-market fit at scale, and subsequently establish international outposts—frequently beginning with a regional general manager based in London or Dublin years after inception.
Artificial intelligence enterprises have entirely abandoned this geographic sequencing. Stripe’s international transaction data indicates that top-tier AI companies penetrate an average of 42 distinct countries within their first year of operation, a figure that expands to 120 countries by their third year. Geographic anomalies underscore this shift; for example, emerging digital economies such as Kazakhstan frequently appear near the top of revenue generation lists for early-stage generative AI tools.
This global footprint translates directly into financial distribution. Across Stripe’s leading AI customer base, an average of 48% of total revenue originates outside the enterprise’s home market. A prominent illustration is Gamma, a San Francisco-based presentation software provider, which achieved $100 million in revenue during its first operational year, with the vast majority of those sales generated internationally.
Geographic expenditure analysis reveals that the United States, Japan, and Germany currently lead in absolute artificial intelligence software spending—correlating directly with national GDP metrics—while South Korea, Brazil, and India represent the fastest-growing regional markets. Consequently, commercial strategists emphasize that localized purchasing infrastructure is no longer optional. Enterprises failing to support regional payment preferences, such as Brazil’s instant payment system Pix or local currency settlement, experience immediate friction and measurable revenue leakage.
The Evolution to Hybrid Usage-Based Pricing Models
The economic mechanics of software monetization have undergone three distinct eras: on-premise perpetual licensing based on installation-day code value, subscription-based cloud pricing reflecting continuous software updates, and now, consumption-based pricing driven by compute and utility.
Among the Forbes AI50 list of elite artificial intelligence companies, two-thirds now employ usage-based pricing models, representing a significant increase from less than half during the preceding summer. This shift is driven by the vast disparity in operational costs and value realization among distinct user profiles. For instance, a software engineer running resource-intensive automated agent clusters overnight consumes exponentially more computational compute than a consumer utilizing conversational AI for basic inquiries. Charging a single flat monthly subscription fee for these vastly different compute profiles inevitably distorts the unit economics of service delivery.
Market validation for this model is evident in the strategic pivot of developer platform Replit. After nearly a decade operating as a traditional developer tool, Replit integrated usage credits on top of its baseline subscriptions as agentic coding accelerated, propelling the company toward a $1 billion revenue run rate. This hybrid structure guarantees predictable baseline revenue for the vendor while allowing monetization to scale efficiently alongside consumer compute consumption.
Industry analysts emphasize that successful usage-based frameworks require strict adherence to consumer-facing transparency. Companies that fail to provide real-time consumption visibility within the product interface—leaving invoicing as the customer’s first indication of accumulated costs—frequently experience elevated churn rates driven by unexpected billing surprises.
Compression of Go-To-Market Operations and Organizational Scaling
Perhaps the most dramatic departure from historical SaaS norms lies in organizational development and go-to-market (GTM) strategy. The established B2B scaling sequence mandated a strict progression: initiate a product-led growth (PLG) motion, build organic adoption, and introduce enterprise sales divisions years later only after proving rigorous product-market fit.
AI-native companies are compressing these sequential phases into simultaneous operations. Companies such as Cursor launched self-serve mechanisms in 2023, rapidly layering sales-led motions to capture enterprise contracts within timeframes that historically required a decade of operational maturation. Concurrently, executive recruitment patterns reflect this urgency; industry observers note that an overwhelming majority of early-stage AI founders are actively prioritizing the appointment of a Chief Revenue Officer (CRO) within their company’s first year.
This structural compression requires unified financial and operational infrastructure. Enterprises that assemble revenue operations piecemeal—utilizing fragmented third-party vendors for billing logic, taxation compliance, and payment processing—frequently encounter systemic errors as individual accounts transition dynamically from self-serve consumer tiers to enterprise contracts, or when automated software agents autonomously provision new product features on behalf of a user. Modern revenue architectures must seamlessly track a single customer entity through these multi-tiered operational stages without introducing administrative friction.
Implications for the Broader Technology Sector
The macroeconomic implications of Stripe’s data analysis point toward a permanently altered landscape for venture capital deployment and enterprise software development. By collapsing the temporal gaps between ideation, global distribution, usage-based monetization, and enterprise sales integration, artificial intelligence startups are operating with an operational velocity that outpaces legacy regulatory, financial, and organizational frameworks.
As software agents increasingly bypass human interfaces to discover, evaluate, and procure enterprise tools—evidenced by a tenfold increase in automated agent traffic directed toward API documentation portals—companies failing to optimize their digital infrastructure for both human and machine consumers risk rapid displacement. The empirical evidence demonstrates that modern market leaders no longer choose between localized reach and domestic focus, or between self-serve adoption and enterprise sales; they execute all vectors simultaneously from day one.
Related posts: