Unveiling the 2021 SaaS Survey Part 2: Comprehensive Insights into Software-as-a-Service Trends, Metrics, and Market Evolution

The Software-as-a-Service (SaaS) industry has experienced exponential growth over the past decade, shifting from a disruptive alternative to traditional software licensing into the dominant bedrock of global enterprise technology. As the digital economy accelerates, understanding the granular metrics, operational benchmarks, and financial trajectories of SaaS companies has never been more critical for founders, venture capitalists, and industry executives. To address this growing need for empirical data, the release of the second part of the 2021 SaaS Survey—conducted in strategic partnership between ForEntrepreneurs and KBCM Technology Group—provides an exhaustive look into the health, scaling strategies, and financial performance of modern cloud-based businesses.
Building upon the foundational findings established in the first installment of the survey, this comprehensive report serves as an invaluable diagnostic tool for stakeholders navigating an increasingly competitive and capital-rich market environment. By synthesizing data collected from hundreds of private and public SaaS companies, the 2021 survey illuminates the shifting paradigms of customer acquisition, retention dynamics, sales efficiency, and capital allocation. This analysis breaks down the core revelations of the second part of the survey, offering context, historical perspective, and actionable intelligence derived from the industry’s leading benchmark study.
Background and Context of the KBCM SaaS Survey Partnership
For over a decade, the annual SaaS Survey published jointly by ForEntrepreneurs (led by renowned entrepreneur and investor Alistair Croll and prominent startup advisors) and KBCM Technology Group (a premier investment banking arm specializing in technology sectors) has been widely regarded as the gold standard for industry benchmarking. In the fast-paced world of technology startups, anecdotal evidence often supersedes empirical reality. Founders frequently struggle to determine whether their churn rates, sales cycles, or research and development expenditures align with healthy industry standards.
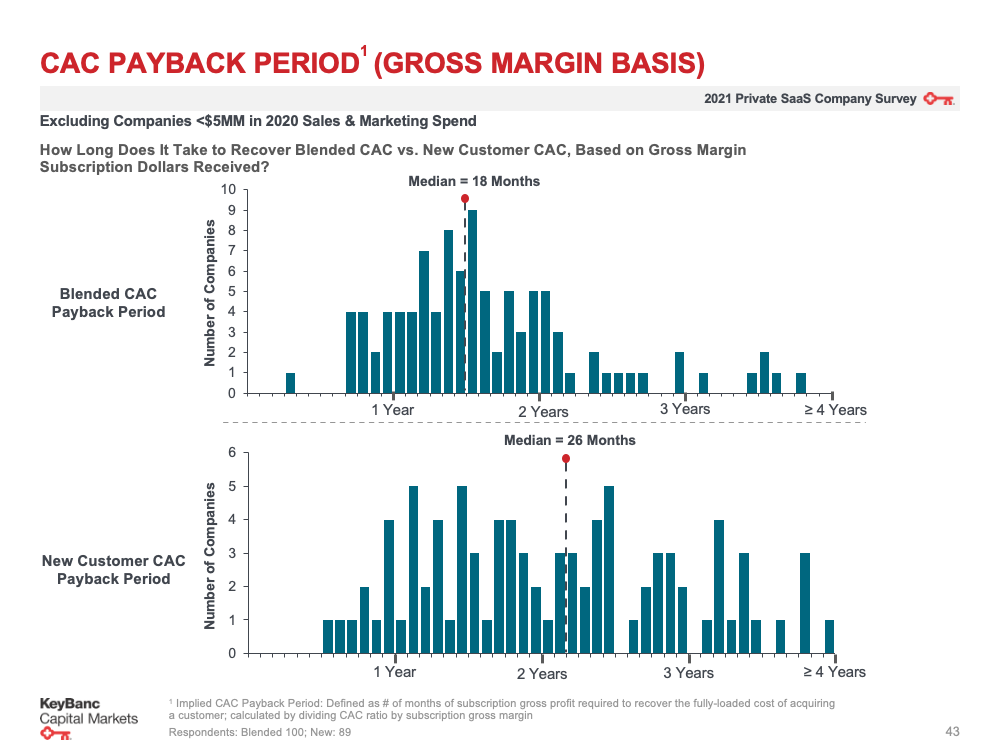
The KBCM partnership was forged to eliminate this guesswork by compiling rigorous, aggregated data across a diverse cross-section of the SaaS ecosystem. Participating companies range from early-stage startups generating less than $1 million in Annual Recurring Revenue (ARR) to massive enterprise platforms scaling past $100 million in ARR. By tracking longitudinal data year-over-year, the survey not only captures the immediate snapshot of current market conditions but also highlights secular trends shaping the future of cloud computing.
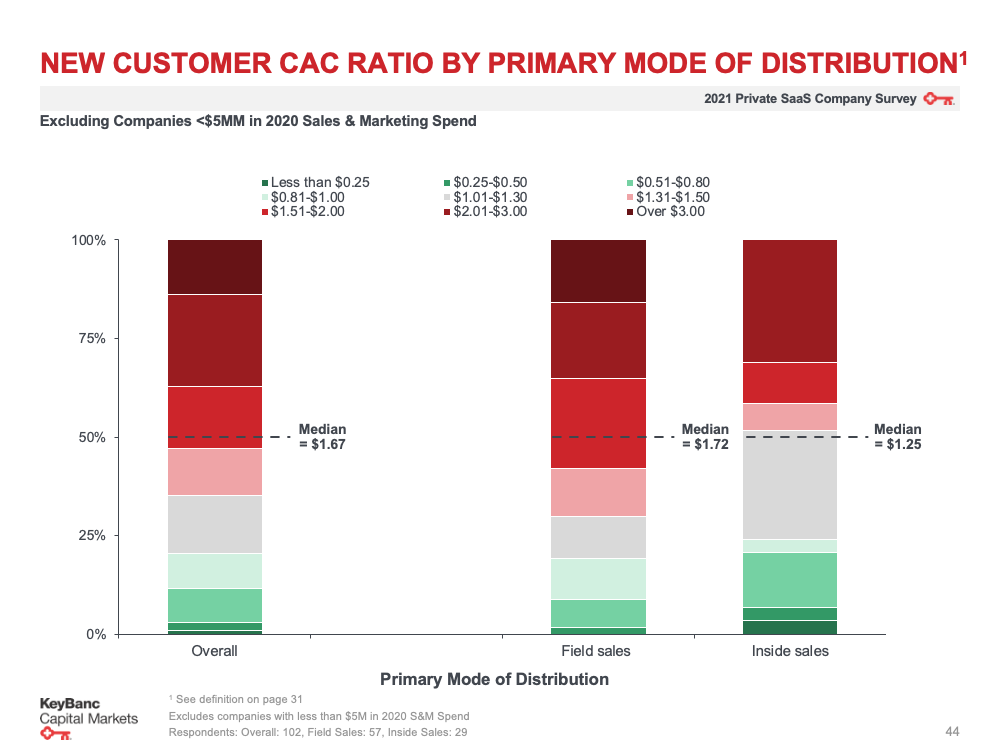
The release of the 2021 survey carried immense significance against the backdrop of the global COVID-19 pandemic and its subsequent economic recovery. The year 2020 triggered an unprecedented acceleration in digital transformation, as remote workforces and digitized supply chains forced enterprises of all sizes to adopt cloud software at a breakneck pace. Consequently, 2021 emerged as a year of historic valuations, aggressive venture capital deployment, and intense competition for talent and market share. Part 2 of the 2021 survey directly addresses how SaaS organizations leveraged this momentum to optimize operations, restructure go-to-market strategies, and secure long-term viability in a post-pandemic economy.
Navigating the 2021 SaaS Survey: Structure and Methodology
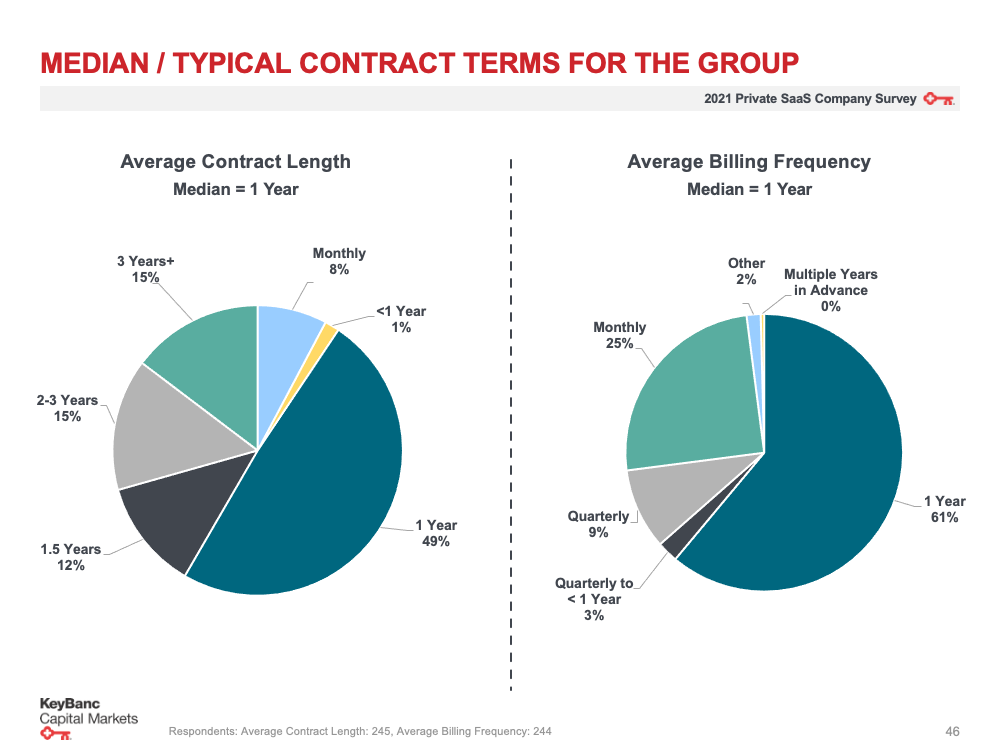
The complete 2021 KBCM SaaS Survey spans dozens of meticulously crafted data slides, divided strategically into two comprehensive parts to ensure readers can digest the massive volume of information effectively. While the first part of the survey focused heavily on top-line growth metrics, customer acquisition costs (CAC), initial funding milestones, and foundational sales models, the second part—featured prominently in the latest data release—dives deep into advanced financial mechanics, operational scaling, gross margins, net retention rates, and organizational scaling.
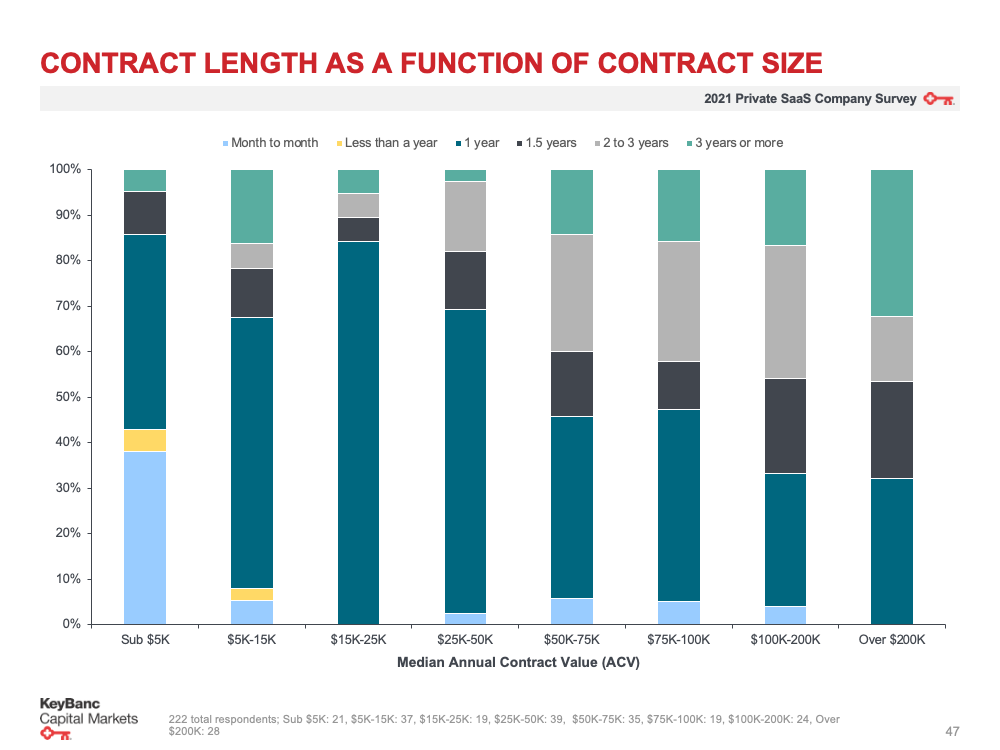
For entrepreneurs and finance leaders, the data presented in Part 2 acts as a compass. It allows leadership teams to benchmark their gross retention, contraction rates, professional services margins, and research and development (R&D) investments against peers of a similar scale. The structured breakdown of the survey data bridges the gap between raw statistical data and strategic execution, providing a clear roadmap for scaling from an emerging startup to a mature, publicly viable enterprise.
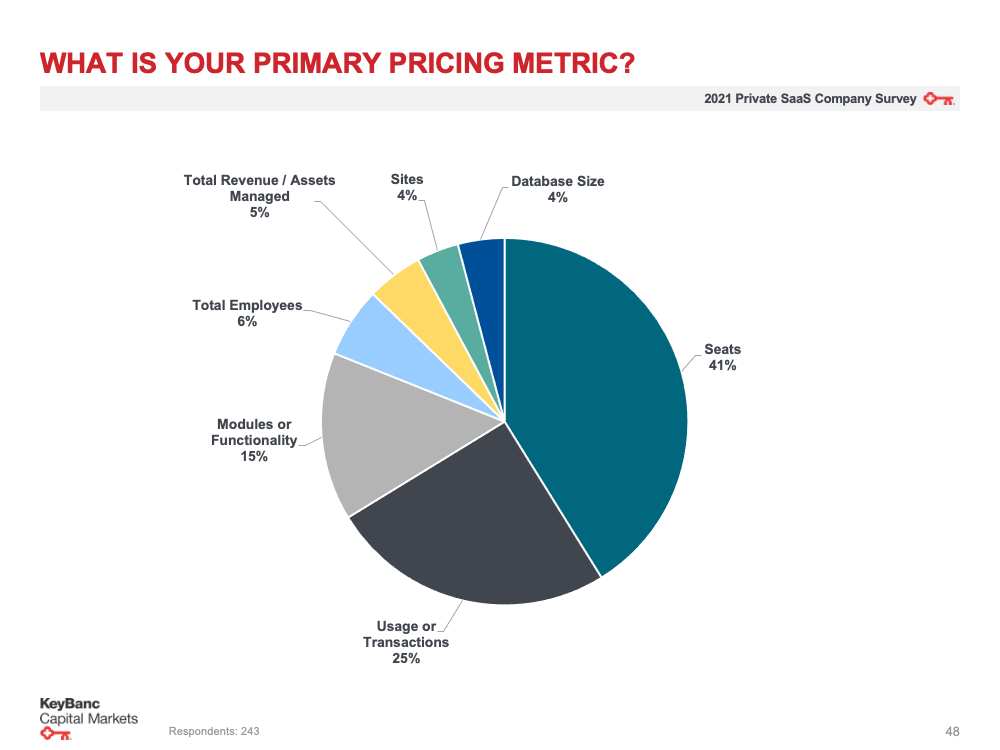
Key Financial and Operational Metrics Explored
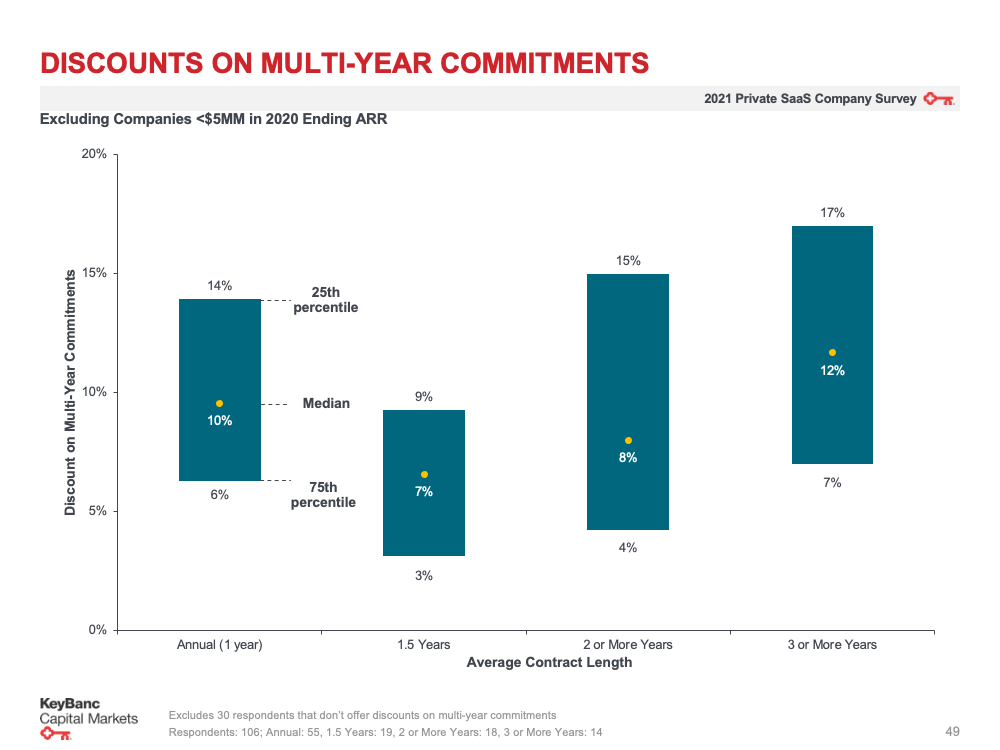
One of the central pillars examined in the second part of the 2021 SaaS Survey is the evolution of unit economics and financial efficiency. In an era where growth at all costs frequently dominated boardrooms, the survey data provides a necessary reality check by emphasizing the importance of sustainable scaling metrics.
Gross Margins and Cost of Revenue
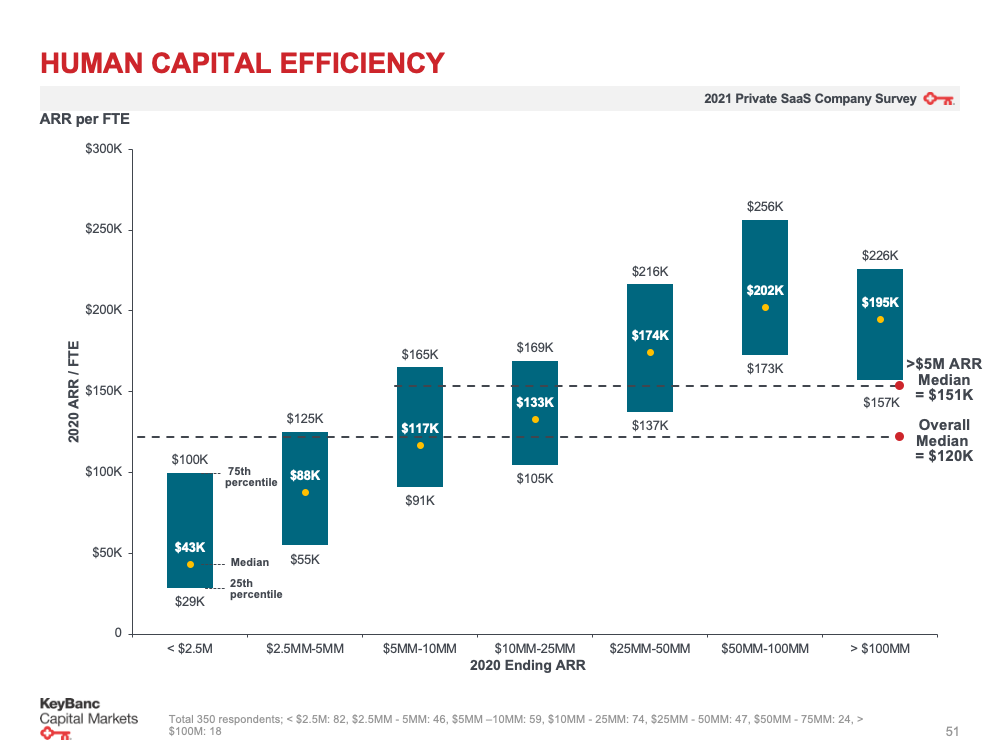
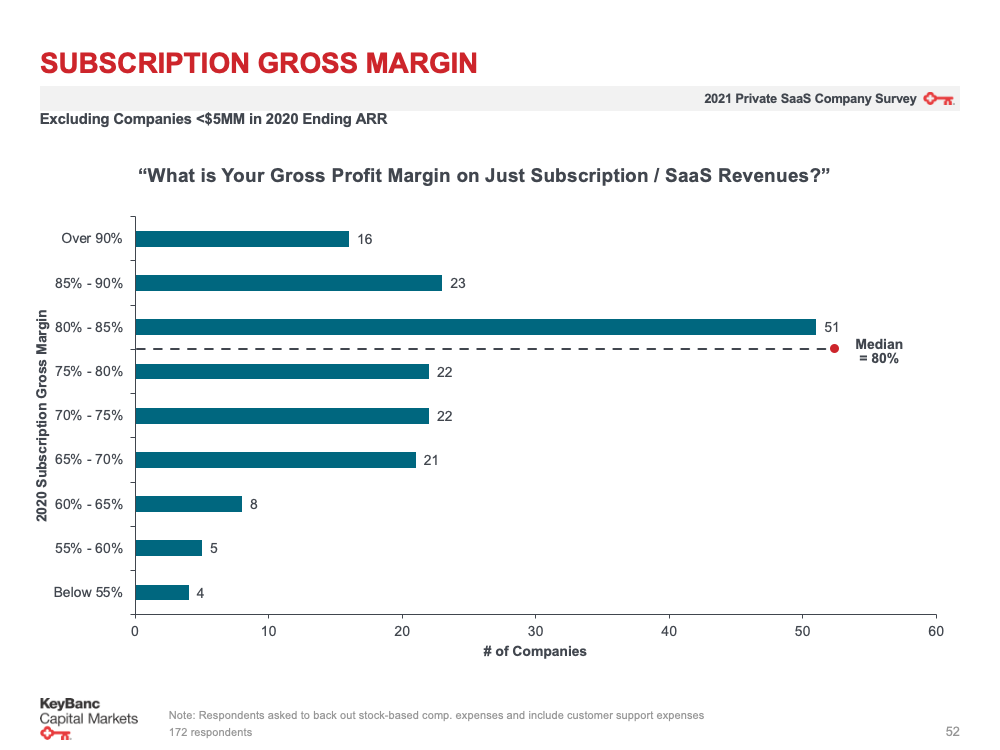
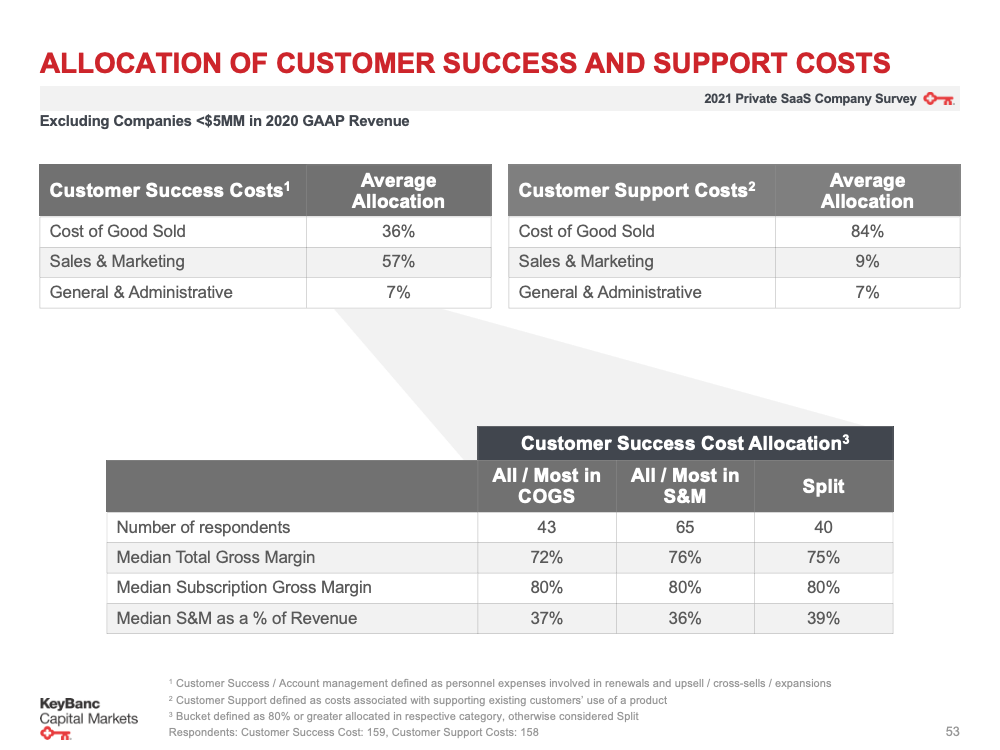
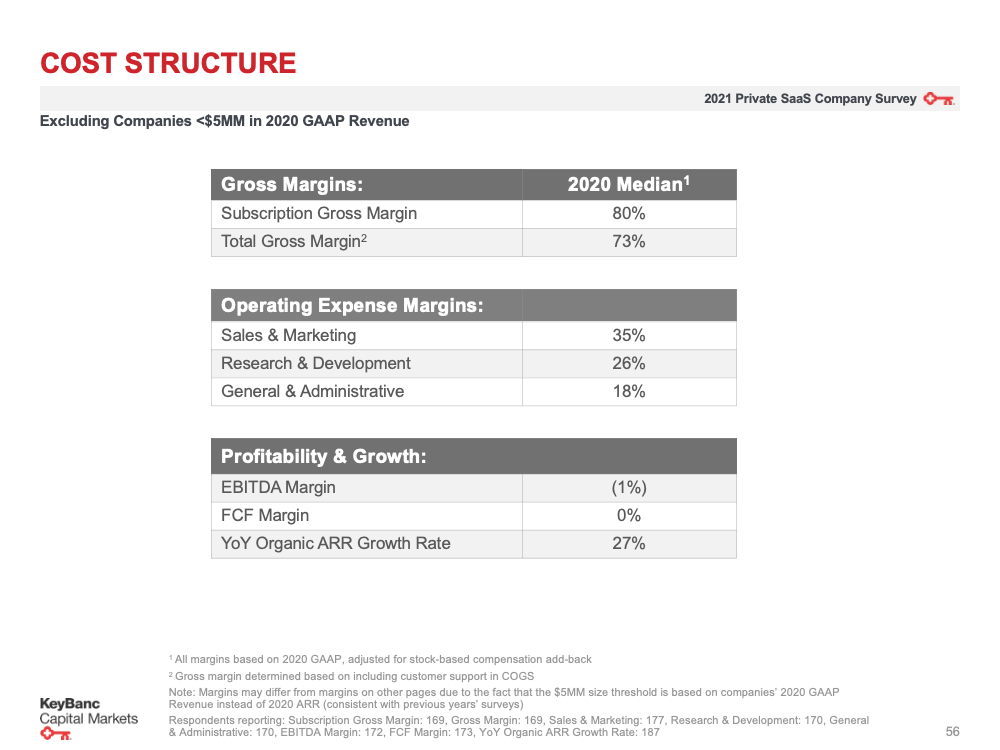
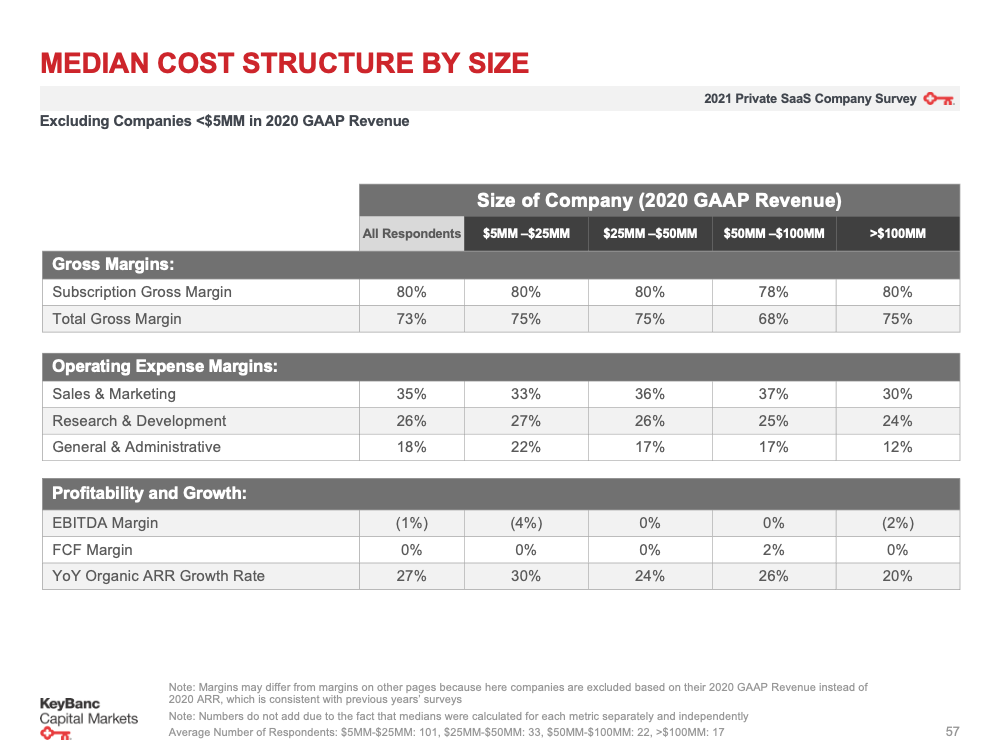
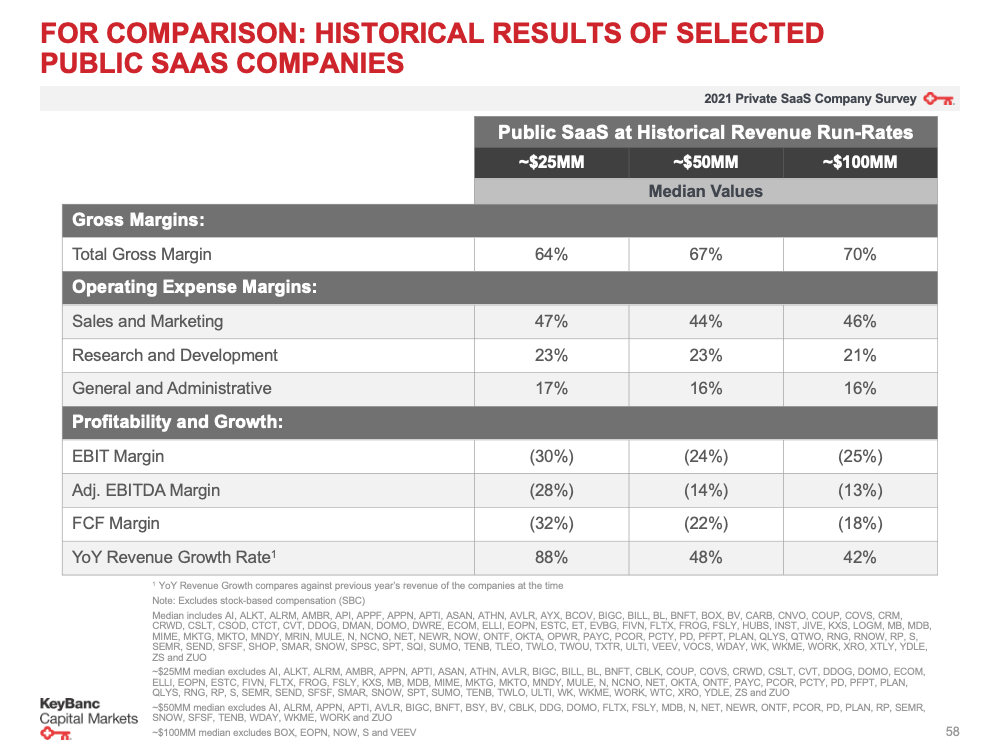
SaaS business models are inherently attractive to investors due to their high gross margins, driven by the scalability of software delivery via the cloud. The survey data outlines how hosting infrastructure, customer support, and professional services impact overall profitability. Companies operating at scale generally report gross margins in the range of 70% to 80% or higher. However, the survey highlights a distinct divergence based on the inclusion of professional services. Businesses that rely heavily on customized implementation often experience depressed gross margins, prompting strategic shifts toward partner ecosystems and standardized, low-touch onboarding processes.
Net Revenue Retention (NRR) and Churn Dynamics
Perhaps no metric is more indicative of long-term SaaS health than Net Revenue Retention (NRR). While gross churn measures the percentage of revenue lost from cancelled subscriptions, NRR accounts for expansion revenue (upsells, cross-sells) from existing customers minus churn and contraction. The 2021 survey underscores that top-tier SaaS companies consistently achieve NRR rates exceeding 110% to 120%, demonstrating a "land-and-expand" motion where customer accounts naturally grow in value over time. The data illustrates how customer success teams have transitioned from mere cost centers to critical revenue-generating engines.
Sales and Marketing Efficiency (The Rule of 40)
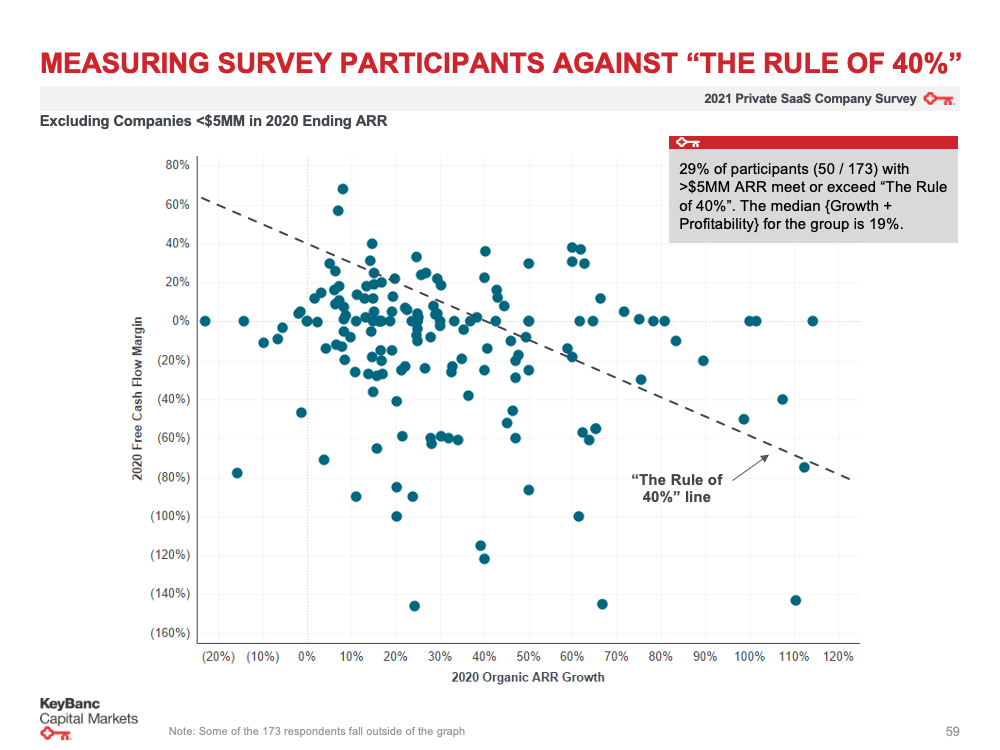
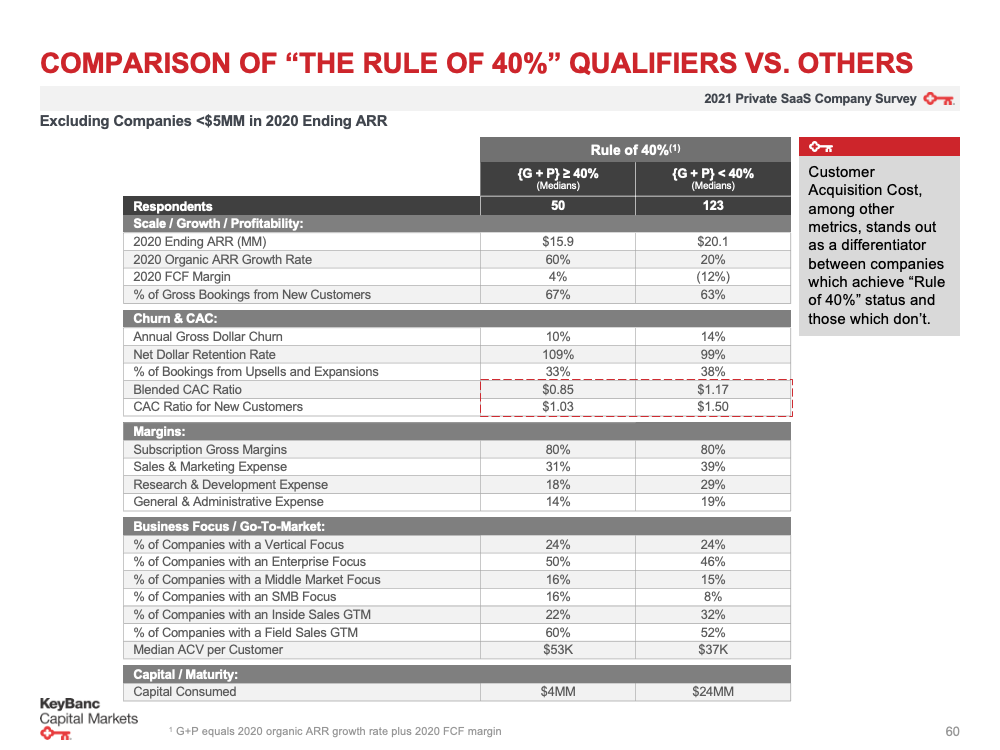
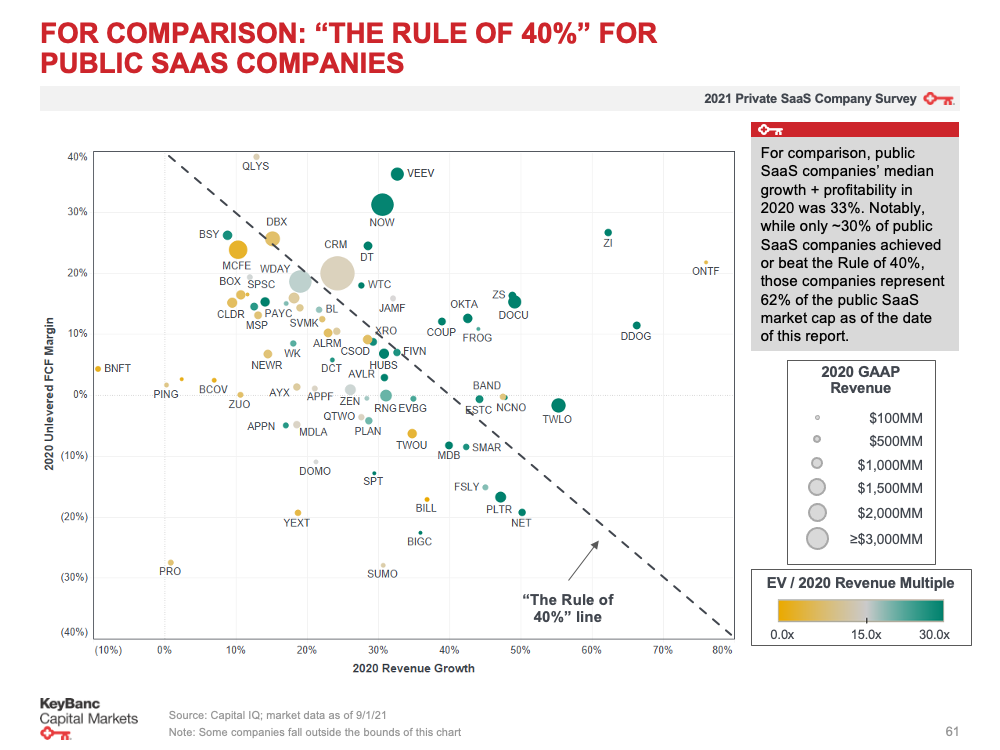
As capital costs fluctuate, investors increasingly rely on composite metrics like the "Rule of 40"—which states that a SaaS company’s growth rate plus its profit margin should equal or exceed 40%—to evaluate financial health. The survey provides critical benchmarks on how companies across different ARR brackets balance aggressive expansion with fiscal discipline. While early-stage startups heavily prioritize hyper-growth with negative cash flows, larger enterprises are expected to achieve a balanced equilibrium of growth and profitability.
The Evolution of Go-to-Market Strategies
The second part of the survey offers profound insights into how SaaS companies structure their sales and marketing organizations to capture market share efficiently. Over the past several years, the traditional enterprise sales model—characterized by large, field-based sales teams targeting executive buyers—has undergone a massive transformation.

The Rise of Product-Led Growth (PLG)
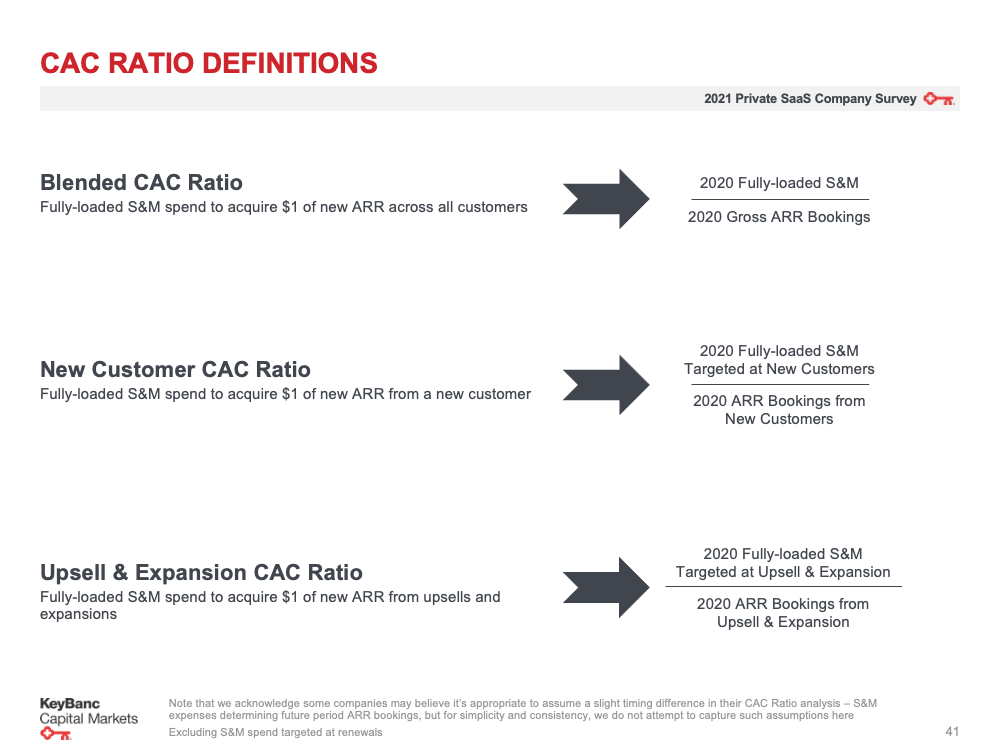
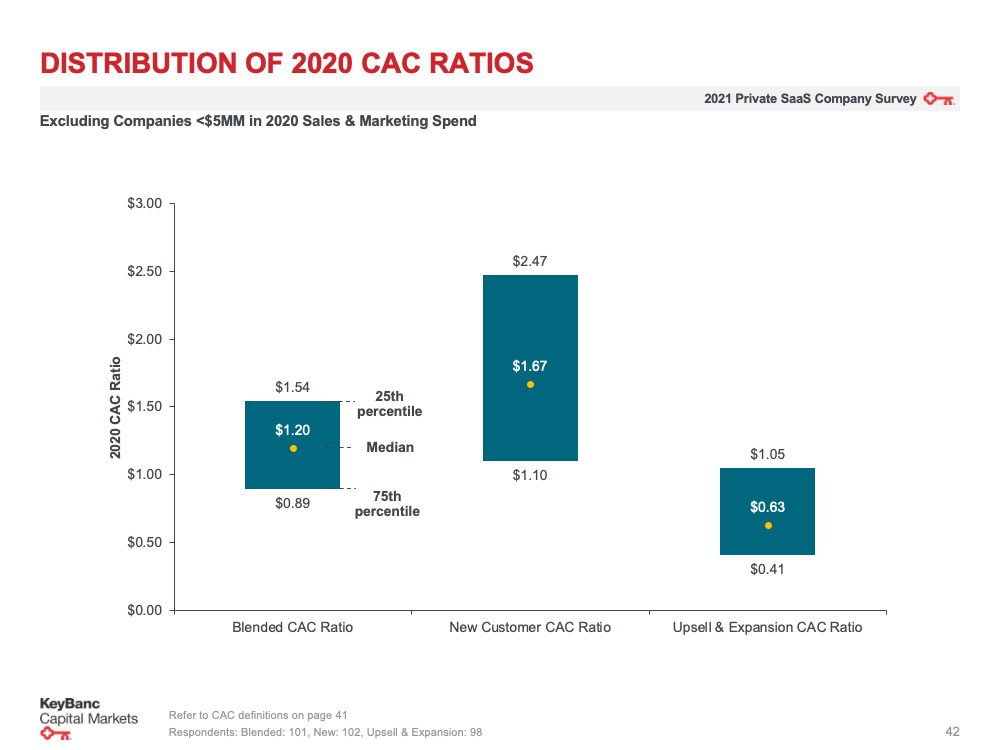
A prominent theme running through the contemporary SaaS landscape is the adoption of Product-Led Growth. Rather than relying solely on top-down sales pitches, PLG companies offer freemium tiers or self-serve free trials, allowing end-users to experience the product’s value firsthand before an organization commits financial capital. The survey data reflects this shift, showing an increasing percentage of companies utilizing self-serve acquisition funnels, particularly in the SMB and mid-market segments. This approach significantly reduces initial Customer Acquisition Costs (CAC) and shortens sales cycles, altering traditional pipeline management metrics.
Enterprise Sales Complexity and Expansion
Conversely, for companies targeting Fortune 500 enterprises, the sales cycle remains complex, multi-layered, and resource-intensive. The survey details the average deal sizes, sales ramp times for account executives, and the quota-to-OTE (On-Target Earnings) ratios prevalent in 2021. These benchmarks enable sales leaders to design compensation plans that align sales team incentives with net retention and multi-year contract renewals.
Industry Reactions and Expert Analysis
Financial analysts, venture capitalists, and SaaS founders have widely praised the release of the 2021 KBCM survey for its transparency and depth. Industry experts note that the data captures a pivotal inflection point in the technology sector—a moment when abundant capital collided with rapid digital adoption, creating both immense opportunities and heightened operational complexities.
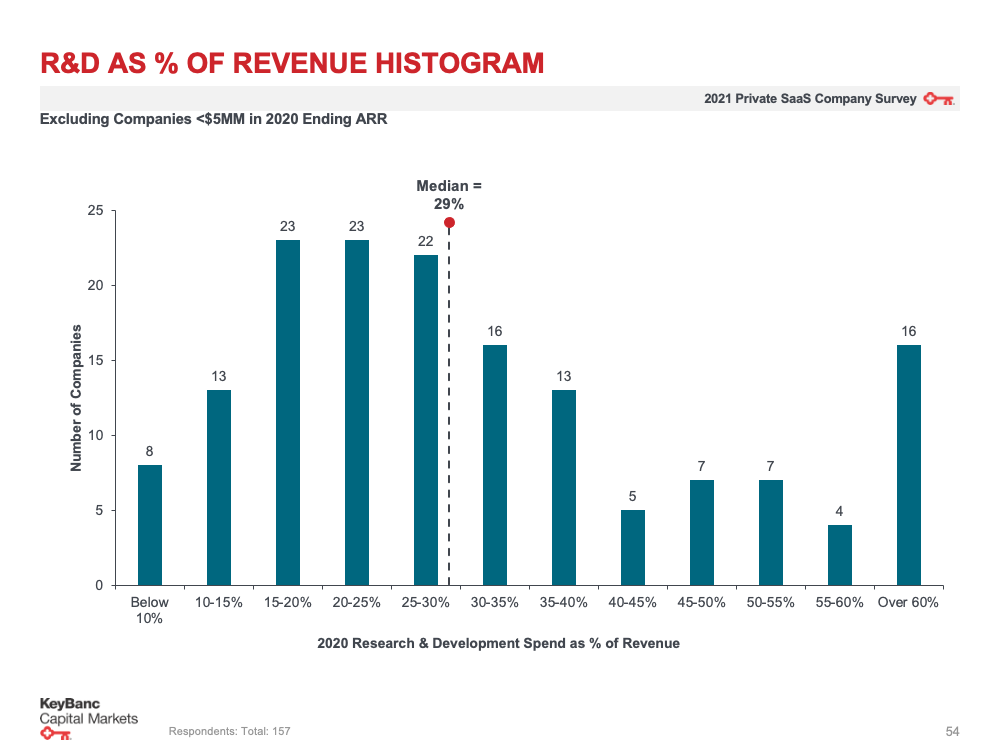
Prominent venture capitalists commenting on the survey have emphasized that while high growth valuations dominated 2021, the underlying data serves as a timeless reminder of operational discipline. Founders who utilize the KBCM benchmarks are better equipped to identify operational bottlenecks early, whether those bottlenecks manifest as high customer churn, bloated sales and marketing expenditures, or inefficient R&D spending.
Furthermore, management consultants specializing in software companies have utilized the survey slides to advise portfolio companies on pricing and packaging strategies. As inflation and macroeconomic pressures began to emerge toward the latter half of 2021, the survey’s insights on pricing power—specifically how companies successfully implemented annual price increases without harming retention—became a vital resource for executive leadership teams.
Broader Impact and Implications for the Future of SaaS
The publication of the 2021 SaaS Survey, culminating in its detailed second part, extends far beyond an academic exercise in data collection. It shapes how the entire software industry operates, allocates capital, and evaluates success.
As the SaaS market matures, investors are no longer willing to reward unbridled top-line growth if it is accompanied by catastrophic unit economics and runaway burn rates. The benchmarks established in the 2021 report provide a quantitative framework for sustainable success. Companies that align their metrics with the upper quartiles of the KBCM survey—particularly regarding NRR, gross margins, and Magic Number efficiency—are structurally positioned to weather economic downturns, secure favorable financing rounds, and execute successful Initial Public Offerings (IPOs) or strategic acquisitions.
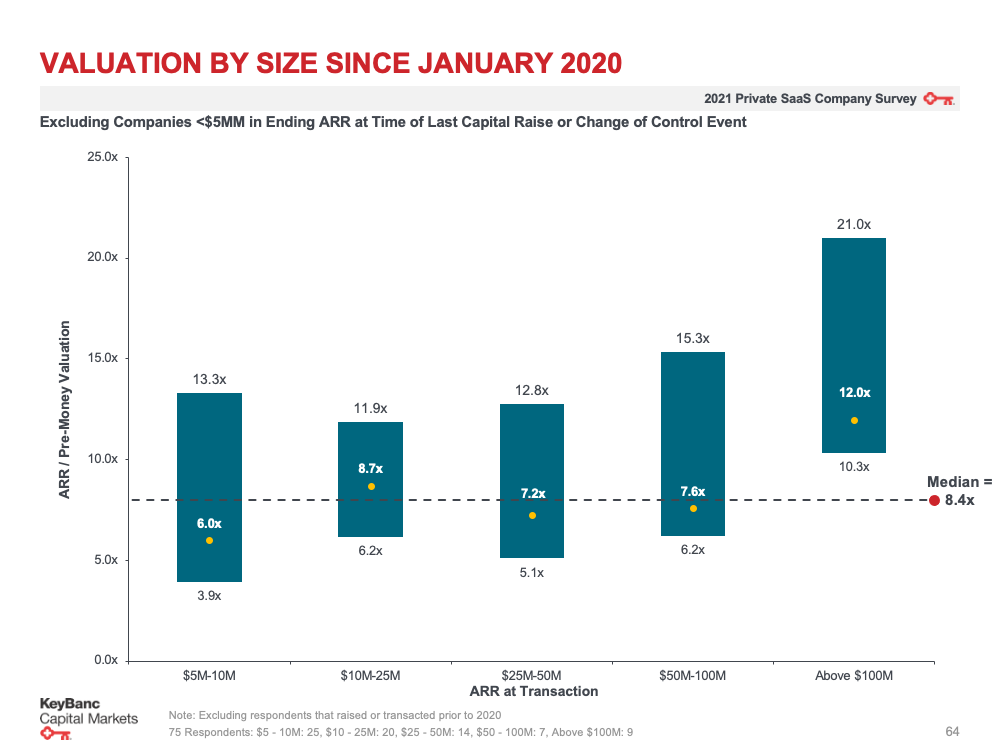
For entrepreneurs embarking on the journey of building a cloud software company, the survey demystifies the path ahead. It offers concrete evidence of what "good" looks like at every stage of growth—from $1 million to over $100 million in ARR. By bridging the gap between theory and empirical reality, the 2021 SaaS Survey cements its legacy as an indispensable tool for the architects of the modern digital economy.
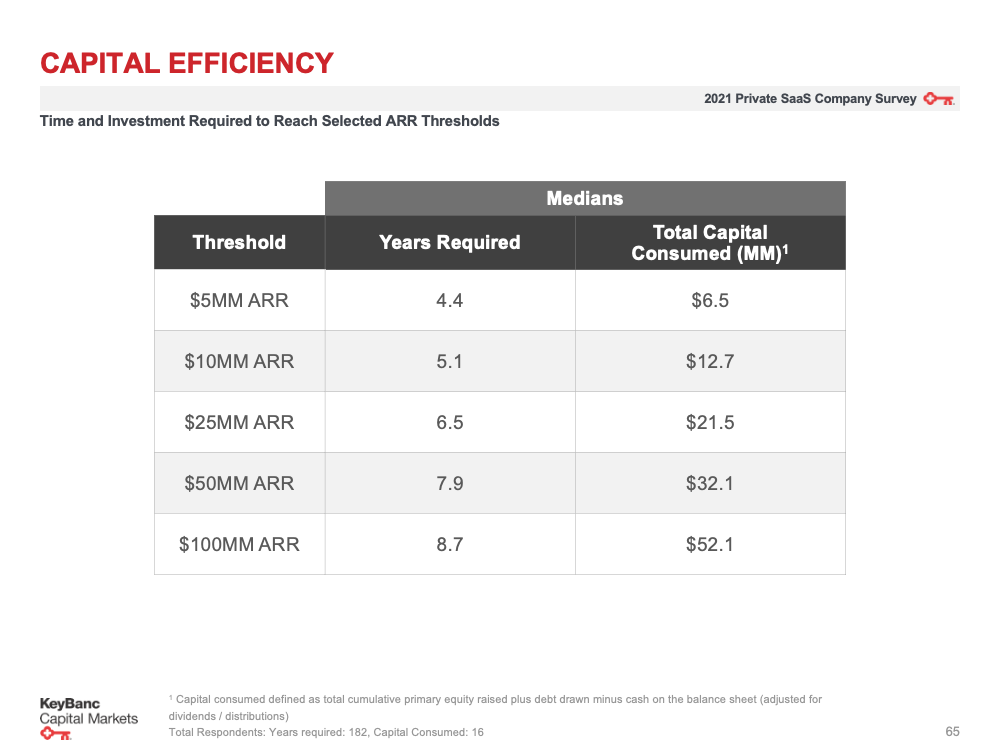
Stakeholders, researchers, and industry participants interested in exploring the complete analytical breakdown, high-resolution graphics, and granular data tables can access the comprehensive PDF version of the 2021 KBCM SaaS Survey through the official ForEntrepreneurs resource portal.