The 7th Annual Private SaaS Company Survey Reveals Key Insights Into Growth, Sales Strategies, and Capital Efficiency

For the seventh consecutive year, industry publication forEntrepreneurs has partnered with the KBCM Technology Group—formerly recognized as Pacific Crest Securities—to release the findings of its comprehensive annual survey examining nearly 385 private Software-as-a-Service (SaaS) companies. This year’s report, spearheaded by David Spitz and the analytical team at KBCM Technology Group alongside contributors from forEntrepreneurs, delivers critical benchmarks regarding the operational and financial health of the private cloud software sector. By shifting the methodology from broad ranges to precise numerical reporting for essential metrics such as Annual Recurring Revenue (ARR), customer churn, and sales and marketing expenditure allocations, the 2018 survey provides an unprecedented, granular look at the economic realities governing private SaaS enterprises in the modern technological landscape.
Background and Evolution of the SaaS Industry Benchmark
To fully understand the significance of the 7th Annual Private SaaS Company Survey, one must look back at the maturation of the cloud computing sector over the past decade. Founded on the promise of subscription-based, recurring revenue models, SaaS transformed enterprise software by replacing high upfront capital expenditures with predictable, scalable operational outlays. However, as the market grew increasingly crowded, founders and venture capitalists alike recognized a severe lack of standardized operational metrics. Early-stage and growth-stage companies often struggled to contextualize their internal burn rates, Customer Acquisition Costs (CAC), and sales efficiencies against broader industry standards.
In response to this knowledge gap, the collaboration between Pacific Crest Securities (now KBCM Technology Group) and forEntrepreneurs emerged as a vital industry barometer. Over seven years, the survey has evolved from a nascent attempt to map out venture-backed software startups into the gold standard for financial benchmarking. The transition in this latest edition to exact figures rather than generalized ranges represents a major leap forward in data integrity, enabling analysts to calculate precise median metrics for the 2017 fiscal year with minimal statistical distortion.
Methodology and Participant Demographics
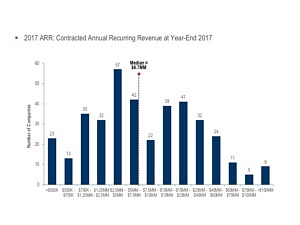
The scope of the 2017 survey encompasses approximately 385 private SaaS organizations, creating a robust sample size that captures companies across various stages of maturity, geographical distributions, and market definitions. Participant composition varied from early-stage startups with under $5 million in ARR to massive private entities generating upwards of $50 million in annual recurring revenue. Specifically, the participant pool included roughly 160 companies with under $5 million in ARR, 65 firms in the $5 million to $10 million bracket, 80 enterprises ranging between $10 million and $25 million, 47 organizations in the $25 million to $50 million tier, and 33 mature companies boasting over $50 million in ARR.
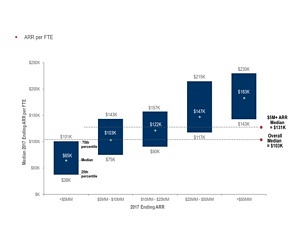
Geographically, the respondents predominantly represented North American technology hubs, though international participation continued to expand, reflecting the globalized nature of modern cloud software deployment. The distribution analysis further demonstrated how human capital efficiency scales with revenue, as measured by ARR per Full-Time Equivalent (FTE). As companies scale, their organizational leverage shifts, impacting headcount growth relative to top-line expansion.
Organic Growth Trends and the Reality of Hyper-Growth at Scale
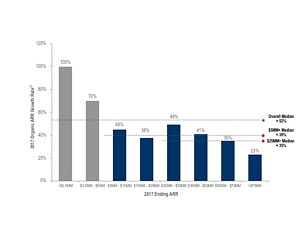
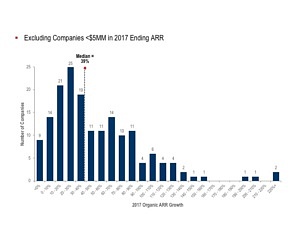
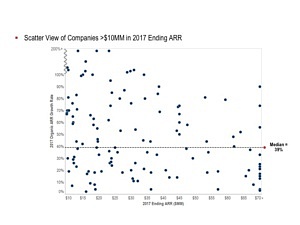
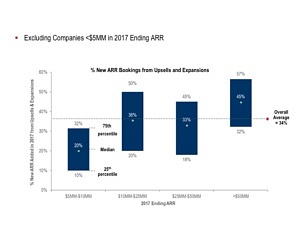
One of the most striking revelations in Part One of the report centers on organic Annual Recurring Revenue growth rates, which explicitly exclude inorganic expansion driven by mergers and acquisitions. Among the 261 respondents who detailed their organic growth figures for 2017, the median growth rate hovered around the 40% mark, though performance varied heavily depending on the baseline revenue size of the company.
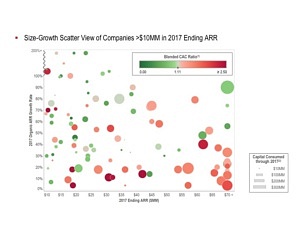
The survey data reveals a distinct structural reality within the SaaS ecosystem: a long, sparse "tail" of high-performing outliers exists above the median, but true hyper-growth becomes exceedingly rare as companies scale. For startups under $2.5 million in ARR, maintaining triple-digit growth rates is achievable through initial market penetration and product-market fit validation. However, as organizations surpass the $50 million and $75 million thresholds, maintaining rapid percentage growth requires massive absolute dollar additions, causing median growth rates to taper off significantly.
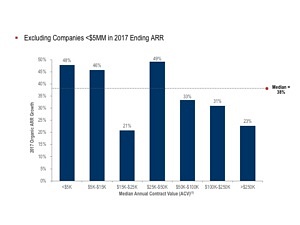
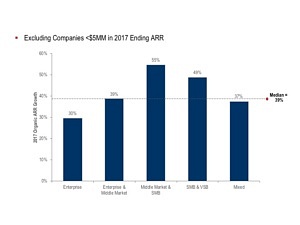
Furthermore, the research investigated median growth rates as a function of target customer demographics and Annual Contract Values (ACV). Enterprises targeting large corporate clients (defined as organizations with over 1,000 employees) demonstrated different scaling trajectories compared to those focusing on Small and Medium Businesses (SMBs) or Very Small Businesses (VSBs). The study categorized median Annual Contract Values across various tiers, showing how smaller contract sizes often correlate with higher transaction volumes, whereas enterprise sales rely on high-value, low-volume contracts managed through sophisticated field sales organizations.

Go-To-Market Strategies: Field Sales Versus Inside Sales
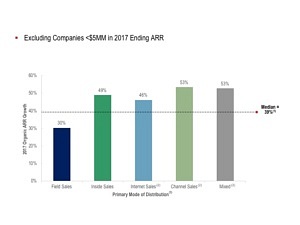
The survey dedicates substantial focus to go-to-market strategies, sales methodologies, and the intricate financial mechanics of Customer Acquisition Cost (CAC). Companies were evaluated based on their primary mode of distribution—defined as the sales channel responsible for the greatest contribution to new sales, provided it outpaced other channels by at least 30 percentage points.
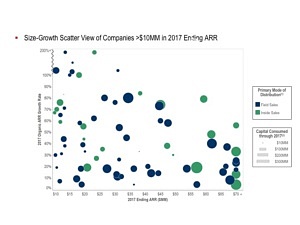
The findings illuminate the traditional divide between field sales and inside sales. Field sales models, typically deployed for high-ACV enterprise contracts, involve heavy travel, lengthy sales cycles, and face-to-face negotiations. Conversely, inside sales leverage digital tools, telecommunications, and remote demonstrations to close mid-market and SMB deals with lower overhead. The report provides a meticulous comparison of these strategies within key crossover deal-size tiers, shedding light on the tipping points where the cost of field sales becomes justifiable relative to the potential contract value.
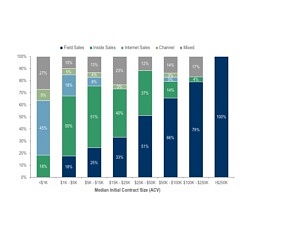
Capital efficiency emerged as another critical focal point. By analyzing total primary cumulative equity raised, plus debt drawn, and subtracting cash on the balance sheet, researchers evaluated how efficiently different distribution models convert capital into sustained ARR growth. The data indicates that internet-driven and inside sales models generally exhibit higher capital efficiency at lower ACV tiers, whereas field-dominant organizations require significantly larger capital infusions to establish enterprise-grade market share.

Sales and Marketing Composition and CAC Payback Analysis
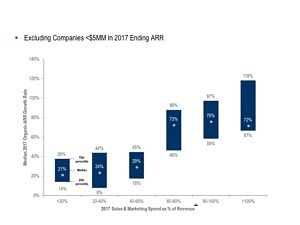
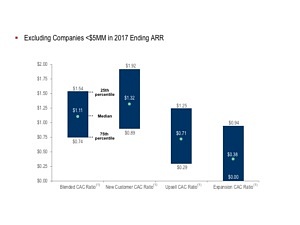
A major highlight of the KBCM and forEntrepreneurs report is its deep dive into Sales and Marketing (S&M) expenditures relative to overall growth. Fully-loaded S&M costs—encompassing salaries, commissions, marketing programs, and overhead—were analyzed against new ARR additions to calculate precise CAC ratios and payback periods.
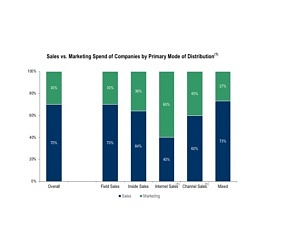
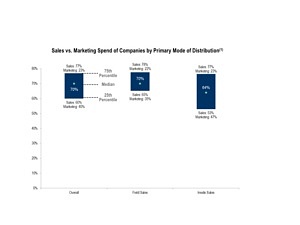
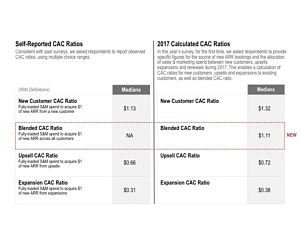
The survey contrasts self-reported CAC ratios with mathematically calculated 2017 metrics, revealing occasional discrepancies in how companies internally measure acquisition efficiency. By breaking down S&M composition into direct sales costs versus marketing expenditures, the report offers clarity on how companies allocate resources across various go-to-market motions. For instance, field-dominant organizations allocate a higher percentage of their budgets to high-touch sales personnel, whereas internet and inside sales models heavily weight their spending toward digital marketing and lead generation infrastructure.
Crucially, the Gross Margin-implied CAC Payback Period—defined as the number of months of subscription gross profit required to fully recover the cost of acquiring a customer—serves as a vital health metric for private SaaS executives. The data demonstrates that while enterprise-focused firms endure longer payback periods due to extended sales cycles and higher upfront costs, their lifetime customer value (LTV) frequently justifies the initial capital outlay, provided churn rates remain strictly controlled.
Industry Implications and Strategic Takeaways
The release of the 7th Annual Private SaaS Company Survey arrives at a time of intense competition and abundant venture capital within the technology sector. Industry analysts and venture capitalists utilize these benchmarks to advise portfolio companies on operational discipline, pricing strategies, and sales efficiency.
The empirical evidence underscores that growth at all costs is no longer a viable long-term strategy for private SaaS firms. Instead, leadership teams must balance top-line expansion with rigorous unit economics, optimizing their CAC payback periods and managing churn to ensure sustainable capital efficiency. As private SaaS companies navigate an increasingly complex macroeconomic environment, the actionable insights provided by KBCM Technology Group and forEntrepreneurs remain an indispensable resource for charting a course toward profitable, long-term enterprise value creation.