The Hidden Financial Risk of Physical Fragility and the Urgent Need for Disability Planning

The intersection of physical health and financial stability is often overlooked until a crisis occurs. Recent data from the Social Security Administration indicates that one in four 20-year-olds will face a disabling condition that keeps them out of the workforce for at least a year before they reach standard retirement age. This statistic underscores a sobering reality: for many professionals, the primary threat to their long-term financial security is not market volatility or inflation, but the sudden, unforeseen erosion of their own physical capacity to work.
The Anatomy of an Unplanned Work Stoppage
The vulnerability of the modern earner was highlighted by a recent series of health-related disruptions that effectively halted professional activity for a period. These incidents, ranging from respiratory issues—specifically asthma exacerbated by post-pandemic stress—to acute musculoskeletal trauma, serve as a case study in how quickly a high-earning individual can be rendered unable to perform essential job functions.
The chronology of these events reveals how rapidly health can decline. Earlier this year, a two-week bout of respiratory illness, compounded by a history of asthma, demonstrated the volatility of health. The inability to maintain a consistent breathing pattern during professional obligations, such as client consulting sessions, resulted in a significant drop in productivity and cognitive energy. This was followed shortly thereafter by an acute back injury, triggered by a combination of high-intensity physical exertion and a failure to account for physiological aging.
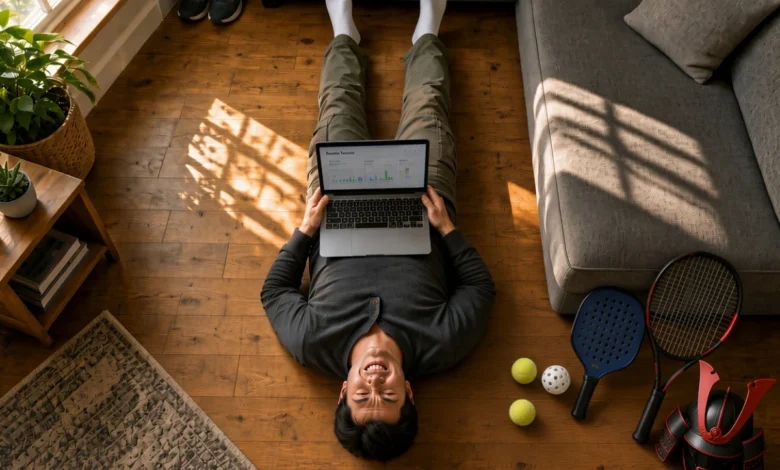
On Sunday, an intense schedule of pickleball was followed by tennis on Monday and heavy weightlifting on Tuesday. By Wednesday morning, the cumulative effect of this physical stress resulted in an inability to perform routine movements, such as walking or bending, without severe pain. This progression—from an active, high-functioning professional to someone incapacitated by physical strain—illustrates that disability is often a mundane occurrence rather than a cinematic disaster.
The Statistical Reality of Disability Claims
While public perception often associates disability with catastrophic accidents—such as vehicle collisions or falls from heights—insurance industry data paints a different picture. According to the Council for Disability Awareness, accidental injuries account for only 9% to 12% of long-term disability claims. Conversely, musculoskeletal issues, including chronic back pain, joint degradation, and related spinal conditions, are the leading drivers of claims, representing between 26% and 33% of all cases.
This shift in the nature of disability has profound implications for financial planning. Because these conditions are often degenerative or sudden flare-ups of chronic issues, they are frequently miscalculated by younger workers who assume their health is a static asset. The financial impact of such an event is compounded by the "elimination period"—the time between the onset of a disability and the commencement of insurance payments—which can leave individuals without income for 90 days or more.
Distinguishing Between Coverage Tiers
For those seeking to mitigate the risk of lost earnings, understanding the nuances of insurance coverage is critical. Short-term disability (STD) acts as a temporary bridge, typically covering 50% to 70% of base income for a period ranging from a few weeks to six months. Many employers provide this as a standard benefit, and specific states like California, New York, and Hawaii mandate state-run programs. However, these are often insufficient for long-term recovery.
Long-term disability (LTD) is designed for more severe, enduring health challenges. It usually triggers after a 90-day waiting period and can provide coverage until the age of 65. The efficacy of an LTD policy often hinges on the specific definition of disability: "own-occupation" policies pay out if the insured cannot perform the specific duties of their current job, whereas "any-occupation" policies may stop benefits if the individual is deemed capable of performing any job, regardless of skill level or salary.
Strategic Financial Mitigation
To safeguard against the risk of physical impairment, financial experts advocate for a multi-layered approach that moves beyond traditional employment-based insurance.
- Individual Policy Supplementation: Group policies provided by employers often have benefit caps that may not adequately replace the income of high earners. Supplemental individual policies, particularly those with an "own-occupation" rider, offer greater protection and portability.
- The Emergency Buffer: A liquid emergency fund is the most effective tool for navigating the elimination period. Financial planners suggest holding between six and 12 months of living expenses in cash or highly liquid, short-term government securities. This ensures that mortgage payments and essential costs are met while insurance claims are processed.
- Diversification of Income Engines: A single source of income represents a single point of failure. The goal of financial independence is to develop multiple "engines"—side hustles or passive income streams—that do not require the individual’s physical presence to function. While manual labor-based side hustles (such as driving or coaching) are susceptible to the same physical risks as a primary career, intellectual property-based ventures (writing, online courses, or content creation) can continue to generate revenue during a period of recovery.
- Front-Loading Savings: The correlation between peak earning years and peak physical health is a finite window. By maximizing contributions to tax-advantaged accounts like 401(k)s and IRAs early in one’s career, individuals create a "financial floor" that remains intact even if their capacity to generate new income drops to zero.
- Proactive Health Management: Treating health as an economic asset requires the same rigor as managing an investment portfolio. This includes prioritizing preventative care, managing stress, and adjusting physical activity levels as one ages. It also involves securing life insurance while in good health; as medical conditions arise, the cost of coverage increases significantly, or coverage may be denied altogether.
Broader Implications for the Workforce
The current economic landscape, characterized by the rise of the gig economy and the increasing frequency of remote work, has changed how disability is managed. Remote work has allowed some professionals to maintain productivity despite physical limitations, but it has not eliminated the necessity for comprehensive insurance.
Furthermore, the reliance on Social Security Disability Insurance (SSDI) as a fallback is a strategy prone to failure. With strict eligibility requirements, a mandatory five-month waiting period, and modest monthly benefit amounts, SSDI is intended as a safety net of last resort rather than a comprehensive financial replacement strategy.
The shift toward individual responsibility for long-term stability requires a fundamental change in perspective. Rather than viewing disability as a distant, unlikely event, individuals must approach their financial planning with the understanding that their physical ability to earn is their most valuable—and most fragile—asset. By building diverse income streams, securing adequate insurance, and maintaining a robust cash reserve, professionals can transition from a state of vulnerability to one of resilience, ensuring that a temporary physical setback does not result in a permanent financial collapse.
In summary, the transition from an active professional life to a state of forced inactivity provides a stark lesson in the necessity of foresight. The objective reality of the modern workplace is that physical limitations are inevitable for a significant portion of the population. Whether through the lens of data-driven insurance planning or the creation of automated income sources, the most prudent course of action is to prepare for the loss of physical capacity while that capacity is still fully intact.