The pursuit of high-growth investment vehicles often necessitates significant financial exposure, yet a recent case study involving a $1 million commitment to a top-tier artificial intelligence venture capital fund highlights the systemic risks associated with capital call schedules. For many investors, particularly those in the Financial Independence, Retire Early (FIRE) community, the traditional venture capital model—defined by long lock-up periods and unpredictable liquidity demands—presents a complex challenge that requires rigorous cash flow management and strategic contingency planning.
The Mechanics of Capital Calls in Venture Capital
Venture capital funds operate on a “blind pool” structure, where limited partners (LPs) commit a specific amount of capital that the General Partners (GPs) deploy at their discretion over the fund’s investment period, typically spanning three to five years. Unlike retail investment vehicles where capital is deployed upfront, venture capital relies on "capital calls"—formal requests for a portion of the committed funds as deal opportunities arise.
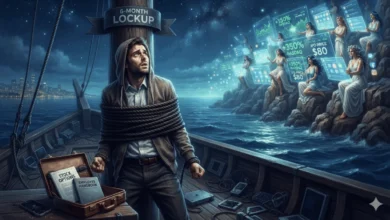
For the investor in this instance, the commitment of $1 million was predicated on a historical modeling assumption: that the fund would call between 20% and 30% of committed capital annually over the first three years. However, the reality of the current AI investment landscape has disrupted these traditional benchmarks. Six months into the fund’s lifecycle, the GP has already called 46% of the committed capital, significantly outpacing the investor’s projected budget. This acceleration is increasingly common in the AI sector, where rapid deal cycles and the use of subscription credit lines allow firms to close transactions with greater velocity.
Chronology of the Liquidity Crunch
The events unfolded following an invitation in March 2026 to join a top-tier venture firm’s AI-focused fund. The investor, motivated by a long-standing "go big" investment philosophy and a desire to participate in the technological shifts driven by artificial intelligence, committed to the full $1 million allocation.
By mid-2026, the discrepancy between the anticipated capital calls and the actual demand became evident. While the investor had budgeted for a $200,000 to $300,000 drawdown in the first year, the actual call amounted to $460,000. This immediate surge in demand for liquidity created a significant strain, as the investor’s liquid assets were insufficient to meet the accelerated pace without liquidating existing long-term holdings.
Financial Implications and Tax Constraints
The primary challenge for an investor in this position is the "tax toll" associated with forced liquidation. Under current U.S. tax law, liquidating long-term investments to meet capital calls triggers a series of costs, including long-term capital gains tax, the 3.8% net investment income tax, and applicable state taxes. In high-tax jurisdictions like California, this can result in an effective tax rate of approximately 33% on the gains realized from the sale.
This scenario represents a classic wealth transfer rather than wealth creation. By selling a stable, performing asset to cover a capital call, the investor loses the compounding potential of the liquidated asset while simultaneously incurring a substantial tax liability. This dynamic illustrates why sophisticated investors often advocate for holding significant cash reserves or utilizing pledged asset lines (PALs) when entering into private equity or venture capital agreements.
Understanding the Legal Framework: The LPA
The Limited Partnership Agreement (LPA) serves as the governing document for these commitments, yet it is frequently misunderstood by retail investors. Key provisions that dictate the flow of capital include:
- Investment Period: This defines the duration during which the GP can call capital for new investments. It does not act as a pacing constraint, meaning the GP retains broad flexibility to call funds at any time.
- Notice Period: Most funds provide a 10-business-day window to wire funds once a call is issued. This short timeline is a critical factor in liquidity risk management.
- Recycling Provisions: Many agreements allow GPs to redeploy early exit proceeds into new investments rather than distributing them to LPs. This can lead to total capital contributions exceeding the original commitment, often capped at 110% to 125%.
- Management Fees: Typically set at 2% of committed capital, these fees are called regardless of whether the funds have been invested in portfolio companies, adding a layer of fixed cost that can exacerbate cash flow imbalances.
The Consequences of Default
Defaulting on a capital call is rarely an option for institutional or high-net-worth LPs. The penalties outlined in standard LPAs are severe, often including the forfeiture of capital accounts, the forced sale of interests at a steep discount, and the potential for legal action. Beyond the contractual penalties, the reputational risk is perhaps the most significant deterrent; venture capital is a tight-knit ecosystem, and a failure to meet financial obligations typically results in being blacklisted from future, highly sought-after investment rounds.
Mitigation Strategies and Strategic Shifts
To navigate these pressures, the investor identified four primary strategies to restore liquidity and meet future obligations:
- Pledged Asset Lines (PALs): By using a taxable brokerage account as collateral, an investor can draw credit at a lower interest rate (often pegged to SOFR plus a margin) to meet calls, thereby avoiding the immediate tax hit of selling assets.
- Active Income Generation: Increasing active income through consulting or business development is a common lever used to bridge the gap between passive income shortfalls and capital requirements.
- Strategic Asset Rotation: Delaying the sale of high-conviction assets until after key milestones—such as a potential IPO or liquidity event—can optimize the timing of tax payments.
- Borrowing from Family Offices or Personal Reserves: While often considered a "last resort," utilizing family capital can provide the necessary bridge to avoid the unfavorable terms of forced liquidation.
Broader Market Context
The trend of accelerated capital calls is not isolated. Many venture firms, facing pressure to deploy capital into the booming AI sector, are increasingly utilizing subscription credit lines. These facilities allow firms to borrow against the unfunded commitments of their LPs to finalize deals quickly. While this benefits the speed of deployment, it shifts the volatility of cash flow to the LP, who must be prepared for larger, less frequent, and less predictable capital calls.
Industry experts note that while venture capital remains a powerful vehicle for wealth accumulation, the J-curve effect—where the fund shows negative or flat returns in its early years due to fees and expenses—combined with aggressive call schedules, necessitates a high degree of financial maturity. Investors are advised to conduct rigorous stress tests on their portfolios before committing to private equity, ensuring that they possess enough liquidity to weather even the most aggressive drawdown scenarios.
Conclusion: The Psychology of Managed Scarcity
For investors who have achieved financial independence, the challenge of managing liquidity can serve as a catalyst for renewed professional engagement. In this instance, the investor acknowledged that the pressure of the capital call acted as a “forcing function,” increasing productivity and forcing a move away from the complacency that can sometimes accompany long-term financial security.
While the strategy of “manufacturing scarcity” is inherently risky, it underscores a fundamental reality of the current economic environment: wealth preservation requires constant vigilance. As the venture capital market continues to evolve in response to the rapid advancement of artificial intelligence, the ability to manage the timing and volume of capital commitments will remain a critical differentiator between those who successfully participate in technological disruption and those who find themselves overextended.
For those considering similar investments, the takeaway is clear: the invitation to invest is only the beginning of the obligation. Thorough due diligence of the LPA, a clear understanding of the fund’s deployment strategy, and the maintenance of a robust, liquid reserve are the essential foundations for anyone looking to navigate the complexities of modern venture capital.