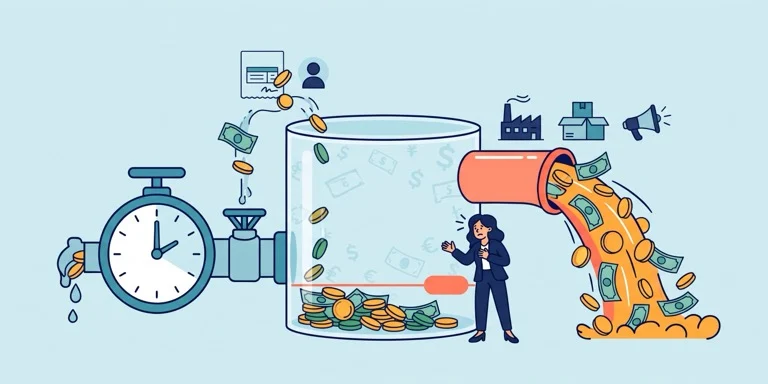
For many entrepreneurs, celebrating a record-breaking sales month is a rite of passage. Sales figures climb, product inventory flies off the shelves, and the financial metrics appear universally positive. Yet, a severe operational vulnerability often looms directly behind this apparent success. When a routine supplier invoice arrives, business owners occasionally discover their operational accounts lack the necessary liquidity to cover the expense. This disconnect highlights a pervasive misconception in modern commerce: the assumption that healthy revenue guarantees financial solvency. In reality, some of the most acute financial crunches routinely afflict enterprises that are expanding rapidly and maintaining robust paper profitability.
Understanding the structural mechanics of modern business finance requires separating two distinct accounting concepts that frequently operate on independent schedules: revenue recognition and cash flow. When a transaction occurs, standard accounting principles record revenue the moment a sale is finalized or a service is rendered. However, the actual liquidity associated with that transaction—the physical or electronic transfer of funds into a business bank account—follows an entirely separate timeline. This divergence creates a temporal gap that catches many first-time founders off guard, forcing them to navigate operational expenses while waiting for client payments to clear.
The Chronology of a Cash Flow Crisis
The genesis of a cash flow crisis rarely stems from poor product-market fit or declining consumer demand. Instead, it typically follows a predictable chronological sequence inherent to scaling an enterprise.
In the initial phase, a company secures a large volume of orders, triggering a surge in monthly revenue reports. Buoyed by these figures, management commits to increased operational output. To fulfill the new demand, the business must immediately procure raw materials or restock inventory. Suppliers generally demand payment upfront or on strict short-term credit frameworks, requiring the enterprise to deploy physical capital instantly.
During the second phase, the newly manufactured or acquired goods are shipped to customers. These transactions are frequently conducted on standard commercial credit terms, such as net-30, net-60, or even net-90 days. While the enterprise has successfully performed its commercial obligation and recorded the corresponding revenue in its ledgers, the actual capital remains tied up in accounts receivable.
In the final phase, overhead expenses—including payroll, facility rent, software subscriptions, and tax obligations—come due. Because the incoming capital from the initial sales has not yet materialized, the enterprise experiences a temporary liquidity shortfall. Financial analysts note that this cycle accelerates during periods of rapid expansion, creating a scenario where a company can simultaneously achieve record profitability on paper while facing immediate insolvency risks.
Supporting Data and Financial Realities
Industry data consistently underscores the danger of conflating profitability with liquidity. According to numerous financial studies tracking small and medium-sized enterprises (SMEs), cash flow mismanagement remains a leading cause of business failure, accounting for roughly 82% of enterprise closures. Crucially, a significant percentage of these failing businesses were technically profitable at the time they ceased operations.
Furthermore, economic research indicates that the cost of scaling an enterprise increases exponentially relative to immediate cash reserves. For every single percentage point of revenue growth, businesses often require a proportional increase in working capital to fund upfront inventory acquisition and marketing expenditures. Because accounts receivable aging reports show that average B2B collection periods continue to stretch—often exceeding 45 days globally—the financial burden placed on growing firms has intensified. Consequently, businesses must maintain liquidity buffers far larger than their monthly net income might suggest.
The Mechanics of Profitable Insolvency
To evaluate the paradox of profitable insolvency, financial experts frequently point to the lifecycle of inventory-heavy business models. Consider a retail enterprise that experiences an unprecedented surge in demand for its flagship product. On a standard income statement, this surge translates into exceptional gross margins and high net income.
However, to sustain this momentum, management must immediately purchase additional manufacturing inputs. This requires an outward cash transfer well in advance of production and delivery schedules. The capital leaves the business bank account immediately. Meanwhile, the newly produced goods require weeks for freight transit and additional months to clear through retail channels.
During this intermediate window, the enterprise holds valuable assets in transit or on shelves, but possesses zero transactional liquidity to service immediate debt or operational overhead. Financial professionals describe this state as a healthy business holding its breath. The underlying commercial model is sound, but the timing mismatch between cash outflows and cash inflows creates a perilous vulnerability.
Strategic Interventions and Industry Responses
Recognizing the structural nature of the revenue-cash gap, financial advisors and fintech platforms have developed targeted frameworks to help enterprises mitigate liquidity risks. Modern strategies focus on two primary operational pillars: accelerating incoming cash velocity and enhancing predictive financial visibility.
Accelerating cash velocity involves tightening accounts receivable protocols. Industry consultants advise enterprises to eliminate delayed invoicing habits, automate payment reminders, and utilize digital payment gateways that reduce friction for clients. Offering minor early-payment discounts or enforcing strict credit limits on habitually late payers are additional measures deployed to compress the collection timeline.
Concurrently, financial visibility has been revolutionized by cloud-based accounting platforms. Modern financial infrastructure tools—such as automated bookkeeping software, real-time bank feed integrations, and predictive cash flow forecasting modules—allow founders to monitor their exact liquidity positioning on a daily basis. By consolidating invoicing, expenditure tracking, and bank balances into a single dashboard, businesses can identify potential cash shortfalls weeks before they materialize.
Broader Economic Implications and Industry Outlook
The systemic vulnerability of growing businesses to cash flow crunches carries broader implications for the wider economy. SMEs serve as primary engines for job creation and macroeconomic innovation. When high-potential enterprises fail prematurely due to liquidity timing issues rather than flawed business models, the broader economic ecosystem suffers from stifled competition and lost productivity.
As commercial credit conditions tighten and macroeconomic pressures fluctuate, financial literacy surrounding working capital management has transitioned from a back-office administrative task into a core leadership competency. Industry observers emphasize that founders must view the management of accounts receivable and payable with the same strategic rigor traditionally reserved for product development and market acquisition.
Ultimately, mastering the distinction between revenue and cash empowers enterprises to scale sustainably. By aligning operational growth with precise liquidity forecasting, modern businesses can navigate the inevitable gap between earning capital and banking it, transforming a historically hidden operational hazard into a manageable, strategic variable.
Related posts: